Nursery Stock Insurance: What Plant Growers Should Know
Plant inventory represents more than the price shown on a nursery’s sales list. It can reflect months of growing time, […]
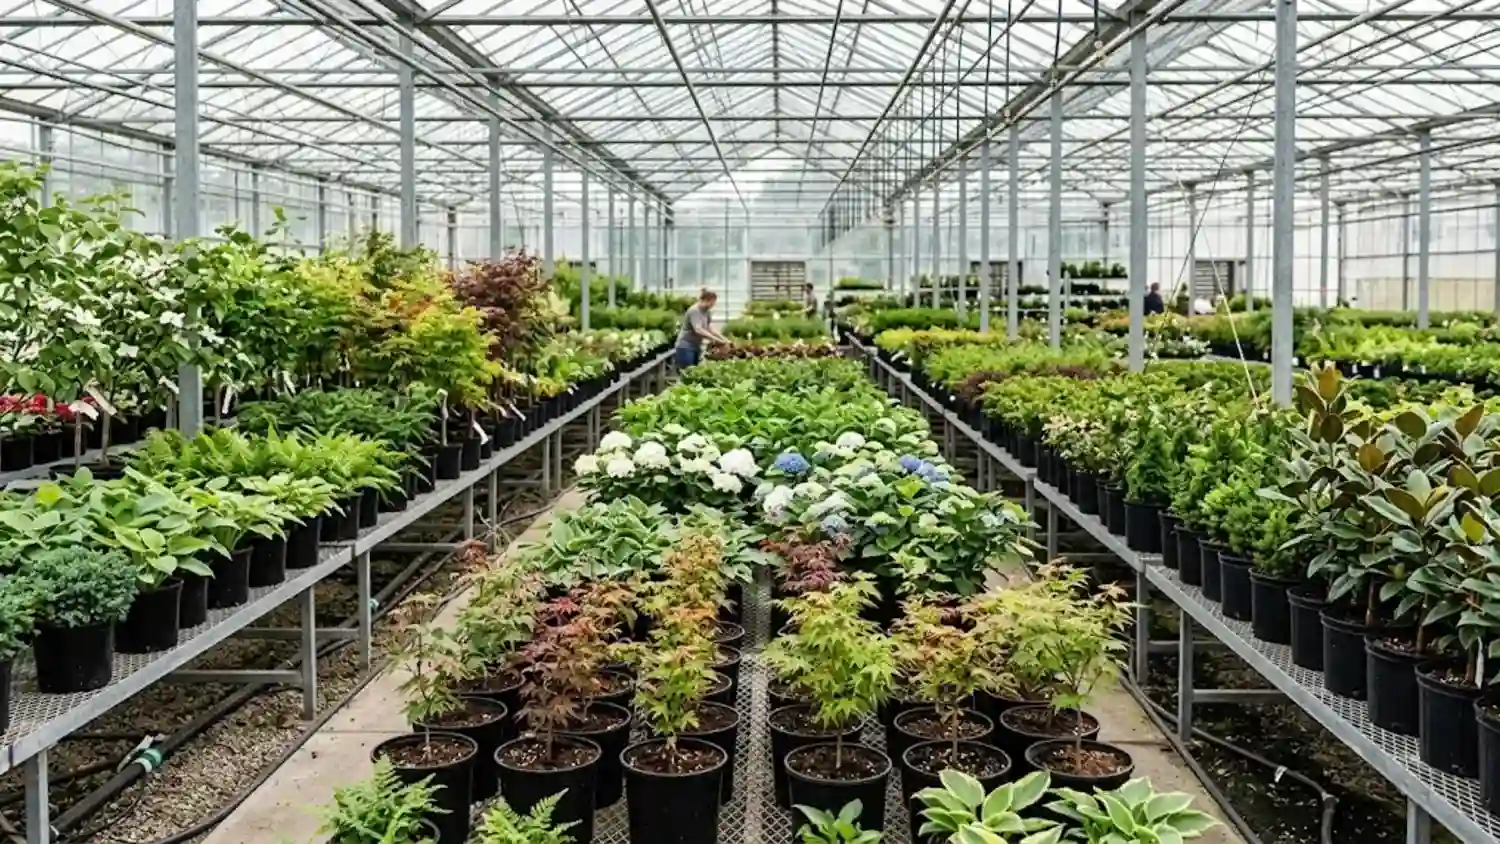

Plant inventory represents more than the price shown on a nursery’s sales list. It can reflect months of growing time, labor, water, fertilizer, containers, growing media, and other expenses. If a large quantity of plants is damaged, the business may lose inventory and struggle to fill customer orders.
Nursery stock insurance refers to insurance options that may help protect eligible plant inventory. However, the term does not describe one universal policy, and it does not mean every plant or cause of loss is covered.
This guide explains the coverage options to investigate, how plant stock may be valued, and which records can help you evaluate your insurance needs.
What Is Nursery Stock Insurance?
Nursery stock insurance is a general term for insurance intended to address financial losses involving plants grown or held for sale. Depending on the operation, protection may involve commercial property insurance, specialized crop insurance, or other coverage arrangements.
These options can differ significantly. A policy covering a greenhouse building may not automatically cover the plants inside it. Likewise, a policy that covers some plant-inventory losses may exclude particular events or impose limits on certain stock.
Before choosing coverage, identify where plants are grown, how they are stored, and whether the inventory includes container-grown plants, field-grown plants, or stock in protected growing structures.
Why Plant Inventory Needs Separate Attention
Plant stock can be difficult to value consistently. Plants of the same species may differ in age, size, condition, growing method, and marketability. A young plant ready for further growing may have a different value from a mature specimen prepared for sale.
Inventory may also be spread across different locations:
- Outdoor container areas
- Greenhouses and shade structures
- Field-grown plots
- Propagation and holding areas
- Shipping and order-preparation zones
A policy may treat these locations or plant categories differently. Give the insurer a clear picture of the growing operation and ask which locations and stock qualify.
Coverage Options for Nursery Stock
Commercial property insurance
Commercial property insurance may cover eligible business property against specified causes of loss. Plant stock, especially outdoor inventory, may be excluded, limited, or subject to special terms.
Ask whether the policy covers plants and whether different conditions apply to greenhouse, container-grown, and field-grown inventory. Confirm the covered causes of loss rather than relying on a general statement that the nursery is insured.
Specialized nursery crop insurance
Some eligible nursery producers may qualify for USDA’s Nursery Value Select (NVS) program. NVS is an inventory-based federal crop insurance pilot that allows eligible producers to select a dollar amount of coverage according to program rules.
Beginning with the 2026 crop year, NVS replaced the Nursery Field Grown & Container program for new purchases. USDA’s eligibility requirements are important: the program is intended for qualifying wholesale nurseries and includes specific conditions involving marketing, plant eligibility, and records.
Review the official USDA Nursery Value Select guidance and speak with an authorized crop insurance agent. Do not assume that a retail plant shop or every type of greenhouse operation qualifies.
Business interruption coverage
A covered property loss can interrupt growing, packing, or selling operations. Business interruption coverage may help with eligible lost income and specified continuing expenses during a covered interruption.
It does not automatically cover every decline in sales, market-price change, unsold plant, or inventory loss. Check what event must occur to trigger coverage and how the policy treats lost income.
How Is Nursery Stock Valued?
The correct valuation method depends on the policy or program. Several different values may be relevant:
- Growing or production cost: The expenses incurred to produce or maintain a plant.
- Expected sales price: The amount the nursery hopes to receive from a sale.
- Replacement value: The cost of replacing eligible property under the applicable policy terms.
- Insured or selected value: A value established under a specific insurance program and its rules.
These figures are not necessarily equal. For example, the anticipated selling price may include expected profit, while the policy may use a defined valuation method.
Before buying coverage, ask how stock values are established, what happens when plants are damaged but still marketable, and which records are required to support a claim.
How to Maintain Useful Plant Inventory Records
Good records help owners understand stock levels and may be essential for meeting insurance requirements.
Keep inventory current
Record plant categories, quantities, growing locations, and relevant dates. Update the information as stock is sold, purchased, transferred, discarded, or otherwise changed.
Save invoices and sales records
Retain supplier invoices, sales invoices, order records, and other documents that support inventory movement and values. If plants are grouped into categories, use a consistent method that makes the records easy to review.
Document damage carefully
If a potential loss occurs, follow the insurer’s reporting instructions. When it is safe and appropriate, take photographs, record the affected locations, and retain relevant documents.
Do not discard or materially alter damaged stock before checking the insurer’s instructions and any applicable policy requirements.
Keep secure backups
Store digital copies of inventory reports, receipts, and photographs in a secure backup location. Backups can help reconstruct records if paper files or local devices are damaged.
For specialized crop insurance, follow the program’s own recordkeeping rules. Ordinary bookkeeping practices do not replace official documentation requirements.
What Affects Nursery Stock Insurance Costs?
Premiums depend on the coverage available and the characteristics of the nursery. Factors may include:
- Types and values of plants
- Growing practices and insured locations
- Local hazards and weather exposure
- Coverage limits, deductibles, and selected values
- Claims history and risk-management measures
- Policy terms and available endorsements
Compare the actual protection provided, not just the quoted price. A less expensive policy may cover fewer inventory categories or have exclusions that matter to your operation.
Questions to Ask Before Buying Coverage
Before purchasing nursery stock insurance, ask:
- Which plants and inventory categories qualify?
- Are container-grown, field-grown, and greenhouse plants treated differently?
- Which locations are insured?
- Which causes of loss are covered or excluded?
- How are damaged plants valued?
- Are deductibles, sublimits, or waiting periods applicable?
- What records must be maintained?
- What steps must be taken immediately after a loss?
- Is business interruption included, or is separate coverage needed?
- How are seasonal increases in inventory handled?
Request written answers to important questions and review the policy documents before relying on a verbal summary.
Common Nursery Stock Insurance Mistakes
Assuming the building policy covers the plants. Structures, equipment, and inventory may be treated separately.
Using outdated stock figures. Old inventory records may not reflect what the nursery actually holds.
Confusing retail price with insured value. The policy may use a defined valuation method instead of the expected selling price.
Overlooking location conditions. Coverage may depend on where plants are grown or stored.
Failing to document a loss. Incomplete records can make it harder to establish quantities, condition, or value.
Frequently Asked Questions
Does nursery stock insurance cover storm damage?
Coverage depends on the specific policy or crop insurance program, the plants involved, and the cause of loss. Wind, hail, flooding, freezing conditions, and other events may be treated differently.
Are plants inside a greenhouse automatically insured?
No. Coverage for the greenhouse structure does not automatically guarantee coverage for the plants, equipment, or supplies inside it. Check each category separately.
Can small nurseries insure plant inventory?
Options depend on the insurer, the business, and the applicable program’s eligibility rules. Small nurseries should describe their operations accurately and ask which coverage options are available.
What records should nursery owners keep?
Maintain inventory reports, purchase and sales records, location information, and photographs or other documentation of damage. Follow any additional policy or program requirements.
Final Thoughts
Nursery stock insurance starts with a clear understanding of which plants are insured, how their value is determined, and which events qualify for coverage. Current inventory records and written answers from an insurer can help you identify gaps before a loss occurs.
For a wider look at business protection, read our guide to plant nursery insurance and its main coverage options. You can also explore small business resources for managing and planning your operation.
Confirm the policy wording and any eligibility requirements with a qualified insurance professional before making a decision.
admin
Practical business guides, useful tools, and technology insights from BusinessNexa.
Work smarter with practical business tools.
Explore useful calculators, guides and tools for modern businesses.