Plant Nursery Insurance: Coverage, Costs, and How to Choose
A plant nursery can look peaceful from the outside, but running one involves plenty of moving parts. Owners invest in […]
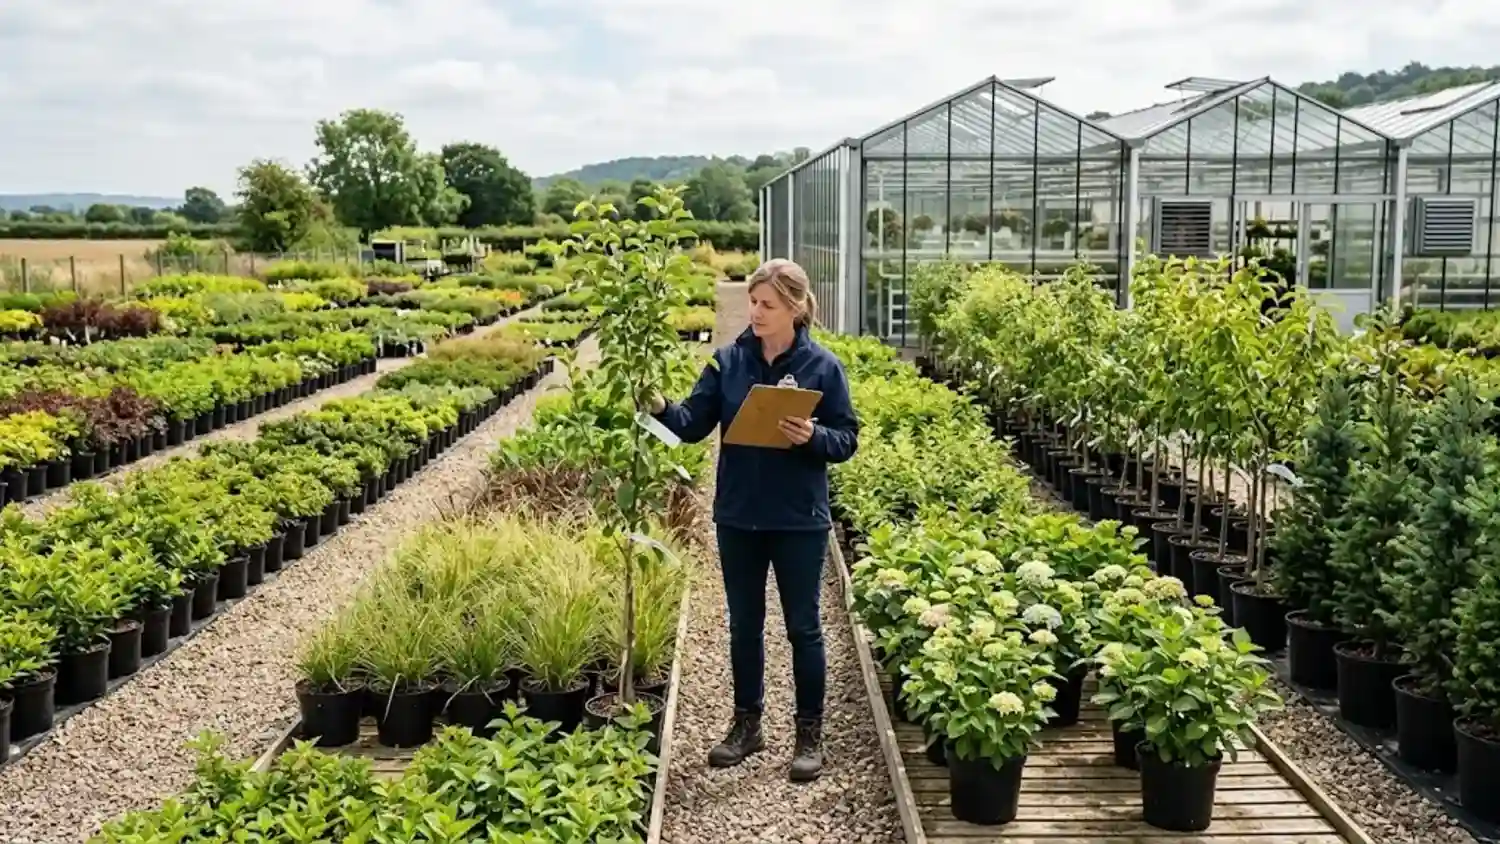

A plant nursery can look peaceful from the outside, but running one involves plenty of moving parts. Owners invest in plants, growing supplies, irrigation systems, buildings, equipment, and staff. They may also welcome customers, fulfill wholesale orders, or deliver plants to landscaping companies. An unexpected loss can affect several parts of the business at once.
Plant nursery insurance helps owners manage certain financial risks associated with these operations. The right coverage depends on what the nursery grows, how it sells plants, which assets it owns, and where it operates.
This guide explains the main types of insurance to consider, what can influence premiums, and how to evaluate policies without paying for coverage that does not fit your business.
What Is Plant Nursery Insurance?
Plant nursery insurance is a combination of business insurance policies selected to address the risks of growing, storing, and selling plants. It is not necessarily a single policy that covers every nursery-related loss.
A nursery might need liability coverage for customer injuries, property insurance for eligible buildings and equipment, and separate protection for certain plant inventory. Businesses with employees or delivery vehicles may need additional policies as well.
Coverage depends on the policy wording, exclusions, limits, deductibles, and any endorsements. A policy that covers a greenhouse building, for example, does not automatically cover every plant growing inside it.
Types of Insurance for Plant Nurseries
General liability insurance
General liability insurance may help with covered third-party bodily injury, property damage, and certain personal or advertising injury claims.
Imagine a customer slips in a wet area near a retail display or a delivery worker accidentally damages a customer’s property. Depending on the circumstances and policy terms, liability coverage may help with eligible claims and legal defense.
Tell your insurer if customers regularly visit the property, attend seasonal sales, or enter loading and growing areas. These details help the insurer understand the operation.
Commercial property insurance
Commercial property insurance may cover eligible buildings, tools, machinery, office contents, and other business property against covered causes of loss.
For a nursery, this might include a storage building, office, potting equipment, or certain irrigation components. Plants, outdoor inventory, shade structures, and greenhouse contents may have different coverage conditions.
Ask the insurer to explain how each property category is treated. Do not assume that protection for the building extends to everything located on the premises.
Nursery stock and crop coverage
Plants held for sale can represent a substantial investment. However, coverage for plant inventory may differ from ordinary commercial property coverage.
Eligible wholesale nursery producers may be able to consider USDA’s Nursery Value Select (NVS) program. NVS is an inventory-based federal crop insurance pilot that lets qualifying producers select a dollar amount of coverage under the program’s rules. Beginning with the 2026 crop year, it replaced the Nursery Field Grown & Container program for new purchases.
Eligibility is specific. USDA’s current NVS guidance includes wholesale marketing and other requirements, so not every retail nursery or greenhouse automatically qualifies. Review the official Nursery Value Select program details and speak with an authorized crop insurance agent before relying on this option.
Greenhouse and equipment coverage
If your nursery uses greenhouses, heating systems, pumps, ventilation, or automated irrigation, review how these assets are insured.
Commercial property coverage and equipment breakdown coverage are not interchangeable. A policy may cover certain physical damage while providing limited or no protection for a particular mechanical or electrical failure. Plant losses resulting from a breakdown may also be treated differently.
Ask which equipment qualifies, what causes of loss are covered, and whether resulting plant damage or lost income is included.
Workers’ compensation insurance
Employees may pot plants, lift containers, operate machinery, load trucks, prune shrubs, or maintain growing structures. Workers’ compensation generally addresses qualifying work-related injuries and occupational illnesses under applicable state law and policy terms.
Requirements vary by state and business circumstances. Confirm the rules that apply to your employees and accurately describe the work they perform.
Commercial auto insurance
If the business owns trucks or vans, or employees drive for deliveries, discuss commercial auto insurance with your agent. Personal auto insurance may not cover every business use.
Explain whether vehicles transport plants, tow trailers, travel between nursery locations, or make customer deliveries.
Business interruption coverage
A covered property loss can prevent a nursery from operating normally. Business interruption coverage may help with eligible lost income and specified continuing expenses during a covered interruption.
Review the policy’s waiting period, restoration period, limits, and exclusions. Do not assume that every sales decline, crop problem, or equipment failure triggers coverage.
How Much Does Plant Nursery Insurance Cost?
There is no single premium that applies to every nursery. Insurers consider the business’s operations, location, property values, claims history, coverage choices, and other underwriting factors.
Common factors include:
- Business size and activities: A wholesale growing operation may have different exposures from a retail nursery with frequent customer visits.
- Property and equipment values: Buildings, greenhouses, machinery, and other assets affect the coverage required.
- Plant inventory: The value and type of stock, along with the coverage available for it, can affect insurance decisions.
- Employees and vehicles: Staffing, work activities, vehicle use, and driving history can influence relevant policies.
- Deductibles and limits: Higher limits may increase premiums, while higher deductibles can leave the business responsible for more of a covered loss.
- Location and loss history: Local hazards, property characteristics, and previous claims may affect underwriting.
Compare quotes using the same business details, limits, deductibles, and coverage options. A lower premium is not necessarily a better deal if important assets or causes of loss are excluded.
How to Choose Coverage for Your Nursery
1. List your assets and activities
Start with an accurate picture of the business. List buildings, greenhouses, irrigation systems, machinery, vehicles, inventory, and other valuable assets. Describe whether you sell retail, supply wholesalers, deliver plants, or provide landscaping and installation services.
2. Document your plant inventory
Maintain records of plant categories, quantities, locations, purchases, and sales. Keep supporting invoices and update the records as stock changes.
If you are considering specialized crop insurance, follow the program’s own documentation requirements. General bookkeeping alone may not satisfy every insurance requirement.
3. Check exclusions and coverage limits
Ask how the policy treats outdoor inventory, greenhouse contents, weather-related losses, flooding, equipment breakdown, and business interruption. Request written clarification when an answer is unclear.
4. Compare complete quotes
Review more than the annual premium. Compare deductibles, sublimits, covered causes of loss, waiting periods, and claim requirements. Also check whether a landlord, lender, or commercial customer requires particular coverage.
5. Review coverage when the business changes
New greenhouses, additional employees, larger inventory, extra vehicles, or new services can change your insurance needs. Review the policy annually and update it when the operation expands.
Common Mistakes to Avoid
Assuming every plant is insured. Plant stock may be excluded, limited, or covered under a specialized policy.
Using outdated property values. An old schedule may not reflect current equipment, building, or replacement costs.
Ignoring business interruption. A covered loss can affect revenue even after physical damage is addressed.
Choosing a policy on price alone. A cheap policy may have restrictive exclusions or limits.
Keeping incomplete records. Inventory reports, receipts, photographs, and sales records can help document a loss.
Frequently Asked Questions
Is plant nursery insurance legally required?
There is no single rule requiring every nursery to purchase the same insurance package. Requirements may arise from state workers’ compensation or vehicle laws, leases, lending agreements, and customer contracts. Check the obligations that apply to your business.
Does general liability cover damage to my own plants?
Generally, general liability is designed for certain third-party claims, not every loss involving the business’s own inventory. Ask about plant stock and property coverage separately.
Does nursery insurance cover storm damage?
It depends on the policy, the property involved, and the cause of loss. Wind, hail, flooding, freezing conditions, and other weather events may have different coverage terms or exclusions.
Can a small nursery obtain insurance?
Small businesses can discuss available commercial coverage with insurance providers. The appropriate options depend on the nursery’s activities, assets, location, and eligibility.
Final Thoughts
Plant nursery insurance should match the way your business actually operates. Start by documenting your assets, reviewing liability exposures, and checking how the policy treats plants, buildings, and equipment separately.
If you operate a wholesale or larger growing business, read our guide to commercial nursery insurance and business coverage options. If plant inventory is your main concern, explore how nursery stock insurance may apply to plant inventory.
Compare written policies carefully and confirm coverage with a licensed insurance professional before purchasing.
admin
Practical business guides, useful tools, and technology insights from BusinessNexa.
Work smarter with practical business tools.
Explore useful calculators, guides and tools for modern businesses.