General Liability Insurance for Small Businesses: A Practical Guide
A customer trips inside your shop. A contractor accidentally damages a client’s property. A business receives a claim alleging that […]
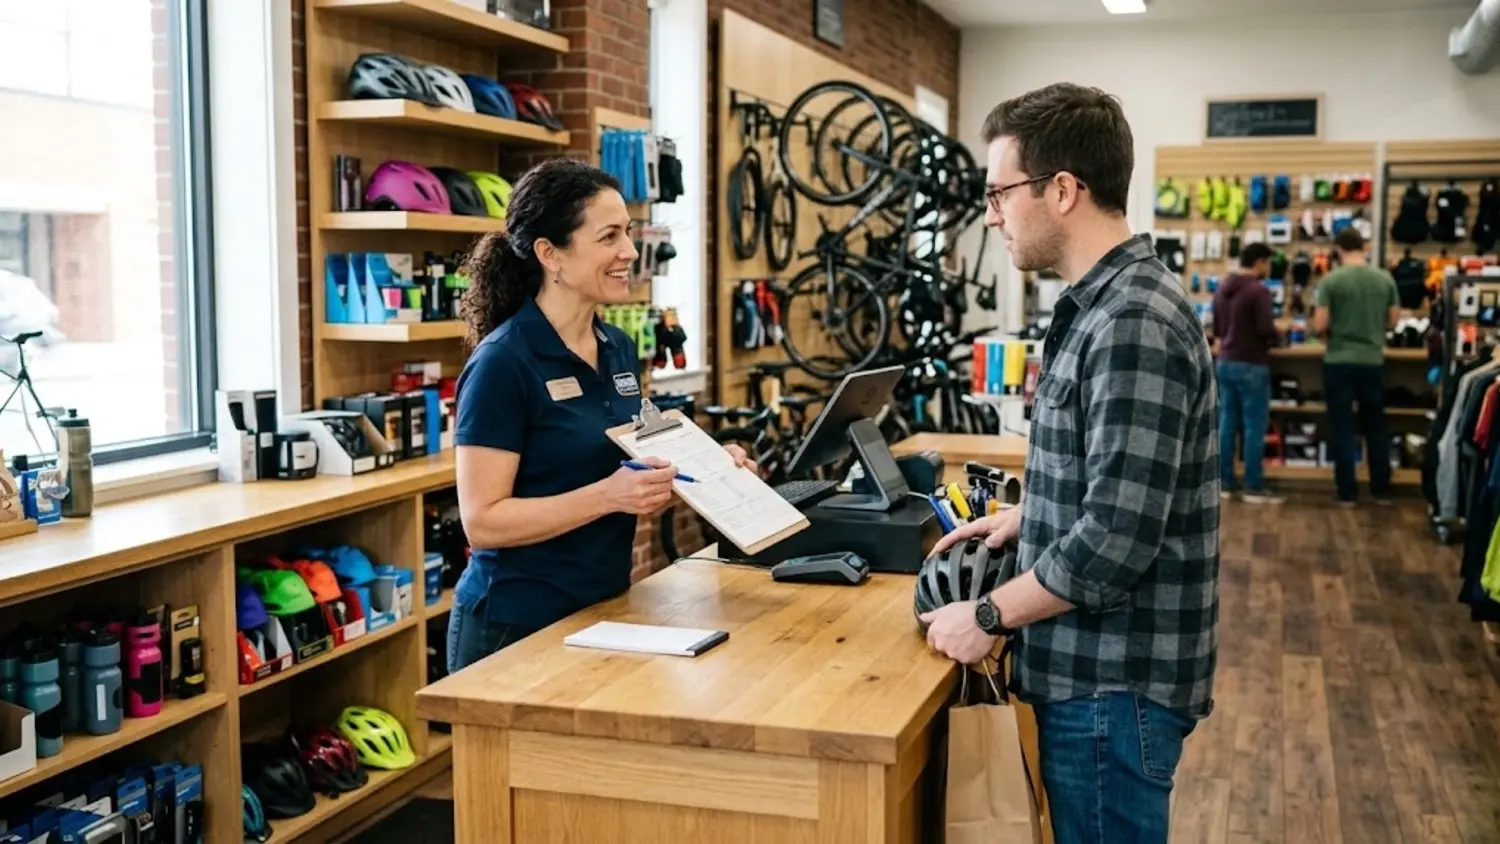

A customer trips inside your shop. A contractor accidentally damages a client’s property. A business receives a claim alleging that its advertising caused harm. Situations like these can lead to legal expenses and financial pressure, even for a small company.
General liability insurance helps address certain third-party claims involving bodily injury, property damage, and specified personal or advertising injuries. Depending on the circumstances and policy, it may help pay legal defense costs and covered damages up to the applicable limits.
It does not cover every lawsuit or business risk. Professional mistakes, employee injuries, commercial vehicle accidents, and damage to your own business property may require other types of insurance.
This guide explains how general liability insurance works, what it may cover, and what to consider before purchasing a policy.
What Is General Liability Insurance?
General liability insurance is a commercial policy designed to address specified claims made by other people or organizations against a business.
It is also commonly called commercial general liability (CGL) insurance. Depending on the policy, it may apply to certain bodily injury, property damage, and personal or advertising injury claims connected with business premises, operations, products, or completed work.
For example, a customer might allege that a hazardous condition at your business caused an injury. If the claim falls within the policy, general liability insurance may help with eligible defense costs and covered damages.
A claim is not automatically covered just because it involves your business. The facts, policy definitions, exclusions, conditions, and limits determine how the insurer responds.
The Insurance Information Institute provides an overview of commercial general liability insurance.
What Does General Liability Insurance Cover?
Coverage varies by policy, but general liability insurance commonly addresses several categories of third-party claims.
1. Bodily Injury Claims
Bodily injury coverage may apply when a third party alleges an injury connected to your business operations or premises.
Examples may include:
- A customer slipping on a wet floor in a store
- A visitor being injured by a hazardous condition at your business premises
- A person alleging injury caused by a covered business activity
If the claim meets the policy’s requirements, coverage may help pay eligible legal defense costs and damages. An injury occurring at a business does not automatically mean the claim is covered.
2. Damage to Someone Else’s Property
General liability insurance may cover certain claims alleging that your business damaged another party’s property.
For example, a service worker might accidentally damage a customer’s wall while completing a job. If the claim qualifies under the policy and is not excluded, insurance may help with covered costs.
Your own equipment, inventory, or building is generally a property-insurance matter rather than a general liability claim. These coverages protect against different kinds of financial loss.
3. Personal and Advertising Injury
Many general liability policies include defined personal and advertising injury coverage. Depending on the policy wording, it may address certain allegations involving libel, slander, or specified advertising-related offenses.
This is not comprehensive protection for every intellectual property, privacy, marketing, or online-content dispute. Definitions and exclusions can significantly affect whether a claim qualifies.
4. Legal Defense Costs and Covered Damages
When a claim falls within the policy, general liability insurance may help pay defense costs and covered damages, subject to the contract and applicable limits.
Legal defense can be expensive even when a business disputes an allegation. Check how defense costs are treated under the policy and whether they reduce the available limits.
Review both the per-occurrence limit and the aggregate limits, along with any deductible or self-insured retention that applies.
What Does General Liability Insurance Usually Not Cover?
General liability insurance is important, but it does not replace every form of commercial insurance.
| Risk | Coverage to investigate |
|---|---|
| Professional errors or negligent advice | Professional liability or errors and omissions insurance |
| Work-related injuries to employees | Workers’ compensation, where required or appropriate |
| Business-owned vehicles | Commercial auto insurance |
| Certain employee-related allegations | Employment practices liability insurance |
| Data breaches and cyber incidents | Cyber insurance |
| Damage to your own equipment or inventory | Commercial property insurance |
| Certain pollution-related claims | Environmental or pollution liability coverage |
These are general distinctions, not a definitive list of exclusions. Some policies or endorsements may provide limited additional protection. Read the actual policy before assuming a risk is covered.
For example, a consultant who provides professional advice may need professional liability insurance even if they already carry general liability coverage. A business with delivery vehicles should review commercial auto insurance separately.
Who Needs General Liability Insurance?
General liability insurance may be useful for businesses that interact with customers, visit client sites, sell products, operate premises, or have contracts requiring liability protection.
Examples include:
- Retail stores
- Contractors and trades businesses
- Cleaning services
- Restaurants and customer-facing businesses
- Event-related businesses
- Landscaping and maintenance services
- Certain consultants and home-based businesses
The right policy depends on the work you perform and the risks you face. Clients, landlords, event organizers, or commercial partners may require proof of coverage before allowing you to work or use their property.
Requirements vary by state and contract. Check the obligations that apply to your business instead of relying on a general rule.
General Liability Insurance vs. a Business Owners Policy
General liability insurance can be purchased as a stand-alone policy or included in a Business Owners Policy (BOP).
A BOP commonly combines general liability with commercial property coverage and often business income protection for eligible businesses. A stand-alone general liability policy focuses on liability exposures and does not automatically insure your own business property.
| Feature | General liability policy | Business Owners Policy |
|---|---|---|
| Third-party liability | Core purpose | Commonly included |
| Business property | Not its main purpose | Commonly included |
| Business income | Not ordinarily a core feature | Often included, subject to terms |
| Policy structure | Stand-alone liability policy | Package policy |
| Additional insurance | Property and other coverage may be separate | Additional coverage may still be needed |
A BOP may be convenient when you need several core protections together. A stand-alone policy may suit a business with different property needs or an arrangement that requires liability coverage separately.
For the full package-policy explanation, see our guide to what a BOP means in insurance.
How Much General Liability Insurance Do You Need?
There is no single coverage limit that works for every business. Your needs depend on your operations, customer exposure, contractual requirements, assets, and ability to absorb a claim.
Consider Your Type of Work
A business that regularly enters customers’ homes or operates at public events may face different exposures from a company that works entirely online.
Review Customer and Public Interaction
Frequent customer visits, public access, physical products, and work performed at third-party locations may affect your risk assessment.
Check Contract Requirements
A client, property manager, or general contractor may specify minimum liability limits or require a certificate of insurance. Review the contract and confirm that the actual policy meets its terms.
Evaluate Your Financial Exposure
Consider the potential cost of defending a claim and paying covered damages. Higher limits may be appropriate for some businesses, but they can also affect premiums.
If your liability exposure exceeds the limits available under a standard policy, ask an insurance professional whether excess or umbrella coverage is appropriate.
What Affects General Liability Insurance Costs?
Premiums vary by insurer and business risk. Common factors include:
- Industry and type of work
- Annual revenue and payroll
- Number of employees
- Location and operating territory
- Claims history
- Coverage limits and deductible
- Products sold or services performed
- Subcontractor use and contract requirements
Do not select a policy based on price alone. A lower quote may have different limits, exclusions, or conditions that do not fit your operations.
Request quotes using consistent business information and compare the actual coverage.
How to Choose a General Liability Policy
Step 1: Describe Your Operations Accurately
Explain the services you provide, products you sell, locations where you work, and any subcontractors you use. Inaccurate information can create problems during underwriting or a claim.
Step 2: Identify Your Main Liability Exposures
Consider bodily injury, property damage, product-related risks, completed work, and relevant personal or advertising injury exposures.
Step 3: Review Limits and Exclusions
Check per-occurrence and aggregate limits, defense-cost treatment, exclusions, deductibles, and any special conditions.
Step 4: Confirm Contract Requirements
If a client or landlord requires coverage, confirm the limits and any additional-insured requirements with your insurance professional. A certificate of insurance summarizes coverage; it does not itself change the policy.
Step 5: Compare Quotes and Review Regularly
Compare similar coverage levels across insurers. Review your policy whenever your services, revenue, contracts, locations, or staffing change.
The U.S. Small Business Administration offers general information about evaluating business risks and insurance options in its business insurance guidance.
Frequently Asked Questions
Is general liability insurance required for a small business?
Requirements depend on state law, contracts, client rules, and business activities. Even when it is not legally required for a particular business, a client or landlord may require it.
Does general liability cover customer injuries?
It may cover certain third-party bodily injury claims, subject to the policy terms, exclusions, and limits. The circumstances determine whether coverage applies.
Does general liability cover damage to my own property?
Generally, your own business property is addressed through commercial property insurance rather than general liability. Review the policy wording to confirm the distinction.
Does general liability cover professional mistakes?
Professional errors and negligent advice are generally outside the main purpose of standard general liability insurance. Businesses that provide professional services should investigate professional liability or errors and omissions coverage.
Can I get general liability without a BOP?
Yes. General liability insurance may be purchased as a stand-alone policy. Whether that is sufficient depends on your property, risks, and contractual or legal requirements.
Final Thoughts
General liability insurance for small businesses can help address covered third-party claims involving bodily injury, property damage, and certain personal or advertising injuries. It can be an important part of risk management, but it does not replace property, professional liability, auto, workers’ compensation, or other coverage that may be necessary.
Describe your operations accurately, compare limits and exclusions, and confirm any contractual requirements before buying. The right policy should match your actual risks—not simply offer the lowest premium.
This article provides general educational information, not individualized insurance or legal advice. Actual coverage depends on the policy contract and applicable law.
admin
Practical business guides, useful tools, and technology insights from BusinessNexa.
Work smarter with practical business tools.
Explore useful calculators, guides and tools for modern businesses.