Commercial Property Insurance for Small Businesses: What to Know
A small business can depend on computers, inventory, tools, machinery, furniture, and physical workspace to serve customers. If a covered […]
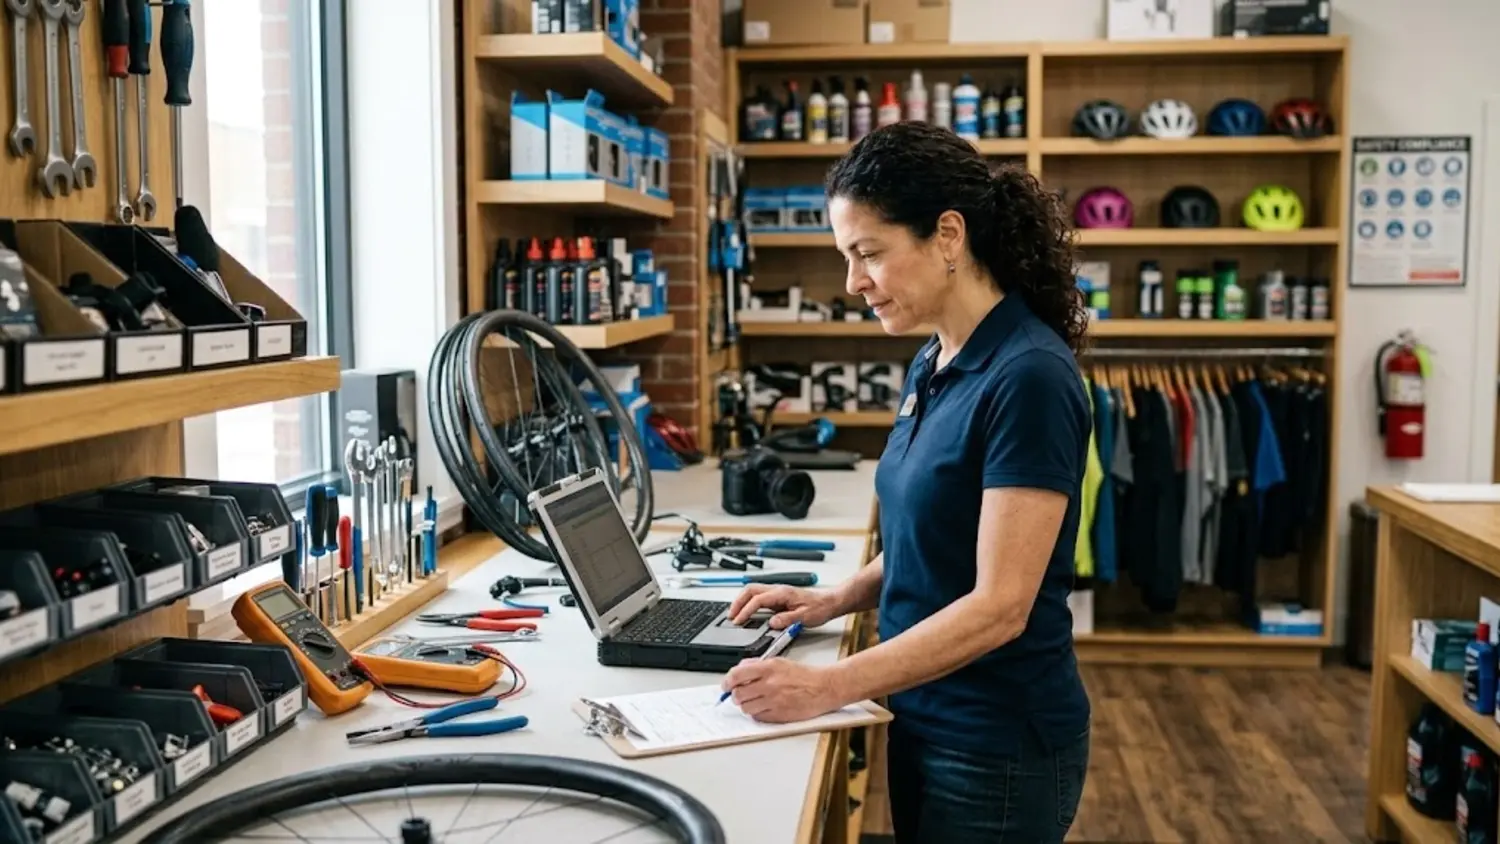

A small business can depend on computers, inventory, tools, machinery, furniture, and physical workspace to serve customers. If a covered event damages those assets, the cost of repairing or replacing them can put pressure on the company’s finances.
Commercial property insurance helps protect eligible business property against covered physical loss or damage. Depending on the policy, it may cover a building, business equipment, inventory, furniture, and certain improvements to leased premises.
Coverage is not identical across insurers. The property insured, causes of loss, policy limits, deductibles, and exclusions all affect how protection works. Understanding these details can help you compare options more confidently.
What Is Commercial Property Insurance?
Commercial property insurance is a type of business insurance that addresses covered physical loss or damage to insured property.
It can be relevant to companies that own their premises as well as businesses that rent space and need to insure their own equipment, inventory, furnishings, or eligible improvements.
A retailer may need to protect merchandise and shelving. A consultant may be more concerned about computers and office equipment. A manufacturer may have expensive machinery, tools, raw materials, and finished goods to consider.
The right policy starts with an accurate picture of what your business owns, what it is responsible for, and how those assets could be damaged.
What Can Commercial Property Insurance Cover?
The policy determines which property is insured and which causes of loss are covered. Depending on the contract, coverage may include the following.
Buildings and Business Premises
If your business owns an eligible building, commercial property insurance may cover the structure against covered physical damage.
If you rent your premises, the landlord may insure the building itself. That does not automatically protect your business contents or improvements. Review your lease and determine which assets and responsibilities belong to you.
Equipment and Machinery
Business equipment can be essential to daily operations. Depending on the policy, covered property may include:
- Computers and office technology
- Production machinery
- Tools and workshop equipment
- Furniture and fixtures
- Point-of-sale systems
- Certain specialized equipment
Maintain an inventory of important assets and check whether high-value items need special limits, scheduling, or separate coverage.
Inventory and Merchandise
Retailers, wholesalers, manufacturers, and product-based businesses may have significant money tied up in inventory.
A property policy may cover insured stock against covered causes of loss. The amount payable can depend on the valuation method, inventory records, policy limits, and conditions.
Review how the policy treats raw materials, work in progress, finished goods, seasonal stock increases, and property stored away from your main premises.
Furniture, Fixtures, and Supplies
Desks, shelving, chairs, cabinets, signs, and other business contents may be covered when they meet the policy’s definitions.
Do not assume that every item used by your business is automatically insured. Read the property definitions and review any special limits.
Improvements to Rented Premises
A tenant may invest in flooring, built-in shelving, partitions, lighting, or other improvements. Whether these items are covered depends on ownership, the lease, policy wording, and any endorsements.
Clarify which improvements belong to you and what the lease requires before selecting coverage.
Which Events May Be Covered?
Depending on the policy, commercial property insurance may cover certain losses caused by events such as fire, lightning, wind, vandalism, or theft.
Two common approaches to property coverage are:
- Named-peril coverage: Applies to the causes of loss specifically listed in the policy.
- Open-peril or special-form coverage: Generally applies to direct physical loss unless the cause is excluded or restricted.
These are general descriptions. The actual wording determines how coverage applies.
Flood and earthquake damage may require separate insurance or an endorsement. Water damage, equipment breakdown, and other specialized risks also need careful review. Never assume a particular event is covered without checking the contract.
The Insurance Information Institute provides additional context in its guide to commercial property insurance for small businesses.
Does Property Insurance Cover Lost Business Income?
Not necessarily. Commercial property insurance primarily addresses covered physical damage to insured property. Business income coverage addresses certain financial losses when a qualifying interruption occurs.
Some Business Owners Policies combine property protection with business income coverage. A stand-alone property policy may require a separate business income option or policy.
Imagine a covered fire damages a small shop. Property coverage may help with eligible repairs and replacement costs. Business income coverage, if included and triggered under its terms, may help with qualifying lost income and certain continuing expenses while the business recovers.
The NAIC’s explanation of business interruption and BOP coverage explains why property protection and interruption protection should be reviewed separately.
For an overview of the package policy that may combine these coverages, see our guide to the meaning of a BOP in business insurance.
Who Should Consider Commercial Property Insurance?
Commercial property insurance may be important for businesses that rely on physical assets, including:
- Retail stores and boutiques
- Offices and professional practices
- Warehouses and distribution operations
- Workshops and light manufacturers
- Contractors with tools or equipment
- Restaurants and other eligible businesses
- Home-based businesses with significant business property
A business with a small amount of portable equipment may have different needs from a retailer with extensive inventory or a company that owns its building.
If you work from home, do not assume a homeowners or renters policy provides adequate protection for business property. Ask your insurer how business assets and business-related exposures are treated.
How Much Commercial Property Insurance Do You Need?
The appropriate limit depends on the property you need to insure and how the policy values it.
Estimate Repair or Replacement Costs
Identify the cost of repairing or replacing your covered property. Do not rely only on the original purchase price or what an item might sell for today.
Replacement-cost and actual-cash-value coverage can result in different claim payments. Actual cash value generally accounts for depreciation, while replacement-cost coverage follows the policy’s replacement-cost terms and conditions.
Account for Inventory Changes
Inventory can rise and fall throughout the year. If stock increases during a busy season, check whether your limits and reporting requirements remain appropriate.
Review Deductibles and Special Limits
A lower premium may come with a higher deductible, lower limits, or restrictions on particular property. Understand how much your business would need to pay after a covered loss.
Consider Business Interruption Separately
Even if your physical property is adequately insured, a temporary closure can create cash-flow pressure. Review whether business income coverage is included, what triggers it, and what waiting periods or restoration limits apply.
What Affects Commercial Property Insurance Costs?
Premiums vary by insurer and underwriting assessment. Common factors include:
- Business location and local hazards
- Building construction and age
- Fire protection and security measures
- Property values and insured limits
- Type of business and operations
- Deductibles and coverage selected
- Claims history
- Inventory levels and specialized equipment
Request quotes using consistent information. Compare not only the premium but also the causes of loss covered, exclusions, deductibles, valuation method, special limits, and available endorsements.
How to Choose a Policy
Before buying, create an inventory of business assets, estimate replacement needs, identify the property you own or lease, and consider which events could cause the most serious financial disruption.
Then compare policies for covered causes of loss, exclusions, deductibles, valuation methods, special limits, business income options, and claims requirements.
Ask about flood, earthquake, equipment breakdown, property away from your premises, and improvements to leased space. A licensed insurance agent or broker can explain options, but you should review the contract before purchasing.
The U.S. Small Business Administration offers general guidance on assessing business risks and considering insurance needs in its business insurance resources.
Frequently Asked Questions
Is commercial property insurance required for a small business?
Requirements depend on applicable law, contracts, leases, lenders, and the business’s circumstances. A landlord or lender may require property coverage even when no general requirement applies to every business.
Does it cover rented business space?
It may cover your business contents and certain eligible improvements, but the building itself may be insured by the owner. Review your lease and policy to understand your responsibilities.
Does it cover theft?
Theft may be covered when included under the policy’s causes of loss and subject to its terms, limits, and conditions. Check any restrictions on particular property.
Does it cover floods?
Flood damage may be excluded from standard commercial property coverage or require separate insurance or an endorsement. Confirm the treatment of flood risk with your insurer.
Is replacement cost better than actual cash value?
Neither is automatically best for every business. Replacement-cost coverage may help pay to replace covered property under the policy’s terms, while actual cash value generally accounts for depreciation. Compare premiums, deductibles, limits, and claim conditions.
Final Thoughts
Commercial property insurance for small businesses can help protect the physical assets that keep operations running. The right policy depends on your property, location, industry, financial exposure, and ability to recover from a covered loss.
Make an inventory, understand exclusions and deductibles, and compare quotes on equal terms. If your business also depends on uninterrupted revenue or faces third-party liability risks, review whether additional coverage or a BOP would make sense.
This article provides general educational information, not individualized insurance or legal advice. Actual coverage depends on the policy contract and applicable law.
admin
Practical business guides, useful tools, and technology insights from BusinessNexa.
Work smarter with practical business tools.
Explore useful calculators, guides and tools for modern businesses.