Small Business CRM Software Excel Financial Model
Building a small business CRM software Excel financial model is less about creating a complicated spreadsheet and more about understanding […]
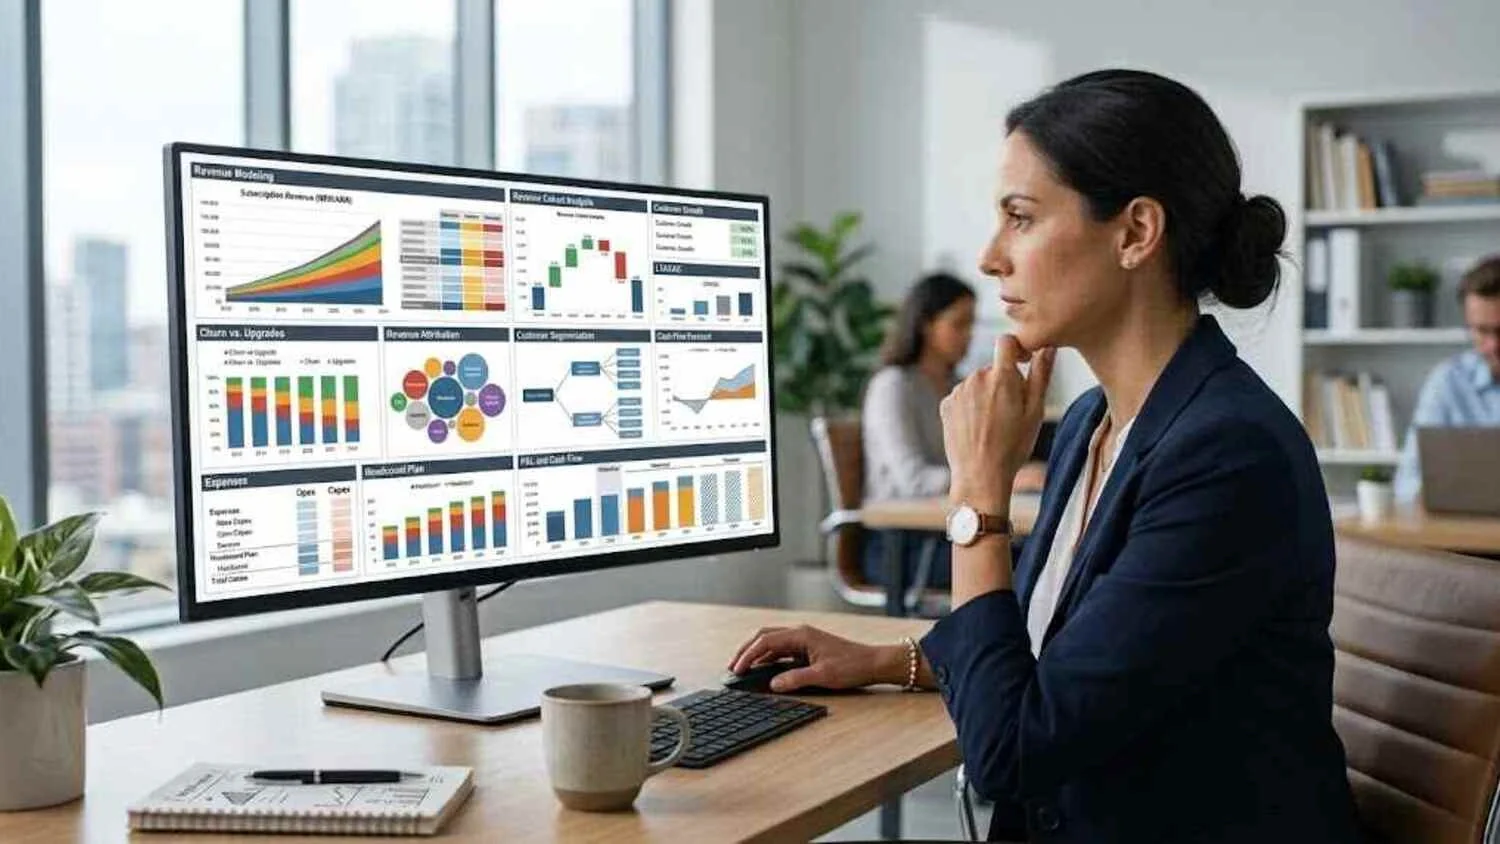

Building a small business CRM software Excel financial model is less about creating a complicated spreadsheet and more about understanding how the business actually makes, spends, and retains money.
A CRM software company may generate recurring subscription revenue, but that does not mean its financial performance can be forecast by simply multiplying customers by a monthly price.
Customers join at different times. Some cancel. Others upgrade. Sales and marketing costs change as the company grows. Software infrastructure creates direct costs, while product development and payroll can create substantial operating expenses.
A useful financial model connects those moving parts.
The purpose of the model is not to predict the future perfectly. It is to create a structured way to test assumptions, understand cash requirements, identify break-even points, and see how changes in growth or retention could affect the business.
This guide explains how to build a practical small business CRM software Excel financial model, including customer growth, MRR, ARR, churn, CAC, LTV, costs, cash flow, break-even analysis, scenarios, and sensitivity testing.
1. Start With the Business Model Behind the Spreadsheet
Before opening Excel, define how the CRM software business actually generates revenue.
A typical SaaS CRM company may charge customers through:
- Monthly subscriptions
- Annual subscriptions
- Different software plans
- Per-user pricing
- Add-on features
- Premium services
- Implementation or onboarding fees
The model should reflect the actual revenue structure rather than assuming every customer produces the same amount of revenue.
For example, a CRM company might have Basic, Professional, and Business plans.
If customers can move between plans, the financial model should eventually be able to represent those changes.
The spreadsheet becomes much more useful when its assumptions reflect the business model rather than simply producing a large collection of formulas.
2. Build the Customer Engine Before the Revenue Statement
Revenue should come from customer activity.
That means the first major section of the model should describe how customers enter and leave the business.
A basic monthly customer model might include:
| Metric | Purpose |
|---|---|
| Beginning customers | Customers carried over from the previous month |
| New customers | Customers acquired during the month |
| Churned customers | Customers who leave |
| Ending customers | Customer base at month-end |
| Net customer growth | Change in the customer base |
A simple relationship is:
Ending Customers = Beginning Customers + New Customers − Churned Customers
This becomes the foundation for the revenue forecast.
If the customer numbers are unrealistic, the revenue forecast will also be unrealistic.
3. Model New Customer Acquisition Separately
New customers should not simply appear as a percentage increase.
Give acquisition its own assumptions.
For example:
- Website visitors
- Lead conversion rate
- Sales-qualified leads
- Trial users
- Trial-to-paid conversion
- Sales-generated customers
- Marketing-generated customers
A simpler model can use a direct assumption such as:
New Customers = Marketing Leads × Conversion Rate
A more detailed model can separate acquisition channels.
This makes it possible to test what happens when conversion improves or customer acquisition slows.
4. Treat Churn as a Core Financial Assumption
Churn is one of the most important variables in a subscription business.
If customers leave every month, the company must continually acquire new customers just to maintain its existing revenue base.
A simple model can use:
Churned Customers = Beginning Customers × Monthly Churn Rate
For example, if the business begins a month with 500 customers and assumes a 2% monthly churn rate:
500 × 2% = 10 churned customers
The model should then subtract those customers before calculating the ending customer count.
Do not hide churn inside a general growth assumption.
Giving it its own input makes the model much easier to analyze.
5. Connect Customers to Subscription Revenue
Once the customer model is working, connect it to revenue.
A basic subscription model can use:
MRR = Paying Customers × Average Revenue Per Customer
However, this becomes more realistic when different plans are modeled separately.
For example:
| Plan | Customers | Monthly Price | Monthly Revenue |
|---|---|---|---|
| Basic | 400 | $25 | $10,000 |
| Professional | 150 | $60 | $9,000 |
| Business | 50 | $120 | $6,000 |
Total MRR would be:
$10,000 + $9,000 + $6,000 = $25,000
This approach makes pricing and customer mix visible.
6. MRR and ARR Tell Different Parts of the Story
MRR and ARR are related, but they should not be treated as interchangeable metrics.
MRR represents recurring monthly revenue.
ARR is commonly calculated as:
ARR = MRR × 12
MRR is useful for monitoring month-to-month movement.
ARR is useful for understanding the annualized scale of recurring revenue.
In an Excel model, keeping both metrics visible makes it easier to see how monthly operating assumptions translate into a larger recurring-revenue picture.
7. Add Expansion Revenue Where It Actually Exists
Some CRM software businesses generate additional revenue from existing customers.
This might come from:
- Additional users
- Higher-tier plans
- Add-on features
- Increased usage
- Additional products
If expansion is part of the business model, do not simply increase the average revenue assumption without explanation.
Create a separate assumption for expansion.
This allows the model to answer a useful question:
How much growth comes from acquiring new customers, and how much comes from existing customers spending more?
8. Model Customer Acquisition Cost Instead of Guessing Growth
Growth requires spending.
Customer acquisition cost, or CAC, helps connect sales and marketing expenditure with new customers.
A basic calculation is:
CAC = Sales and Marketing Spend ÷ New Customers Acquired
For example, if a business spends $20,000 on sales and marketing and acquires 200 customers:
CAC = $20,000 ÷ 200 = $100
The model can then test how changes in CAC affect the company’s cash requirements and growth efficiency.
A business that grows quickly but requires increasingly expensive customer acquisition may have a very different financial profile from one that grows more slowly but acquires customers efficiently.
9. LTV Connects Revenue With Retention
Customer lifetime value attempts to estimate the economic value of a customer over the relationship period.
A simplified subscription model might use:
LTV ≈ Average Revenue Per Customer × Gross Margin ÷ Churn Rate
This is only a simplified approach.
A more sophisticated model can account for expansion, different customer segments, changing churn, and cohort behavior.
The important point is that LTV should not be treated as an isolated marketing metric.
It connects pricing, retention, and gross margin.
10. Look at LTV and CAC Together
CAC becomes much more meaningful when compared with customer value.
If acquiring a customer costs $100 and that customer generates substantial gross profit over the relationship, the acquisition economics may be attractive.
If acquiring the customer costs nearly as much as the economic value generated, growth becomes much harder to sustain.
The model should therefore make CAC and LTV easy to compare.
You can also monitor how the relationship changes under different scenarios.
For example:
- Higher churn
- Higher acquisition costs
- Lower pricing
- Better conversion
- Improved retention
That is more useful than relying on a single “good” LTV-to-CAC number.
11. Separate Direct Software Costs From Operating Expenses
A CRM software business has costs directly associated with delivering the product.
These may include:
- Cloud infrastructure
- Hosting
- Data storage
- Third-party APIs
- Payment processing
- Customer communication services
- Usage-based software services
These costs should generally be considered separately from broader operating expenses.
The distinction helps the model calculate gross margin.
12. Build a Gross Margin View
A simple structure is:
Revenue − Cost of Goods Sold = Gross Profit
Then:
Gross Profit ÷ Revenue = Gross Margin
For a software business, gross margin can be an important indicator of how efficiently recurring revenue translates into money available to cover operating expenses.
If infrastructure or usage costs rise significantly as customers increase, the model should reflect that relationship rather than keeping infrastructure expenses completely fixed.
13. Give Product Development Its Own Budget
Software companies need ongoing product investment.
Development costs may include:
- Software engineers
- Product managers
- Designers
- Quality assurance
- Security work
- Development tools
- Testing infrastructure
Product investment can behave differently from customer acquisition expenses.
Separating these costs helps management see how much of the company’s budget is being directed toward acquiring customers versus improving the product.
14. Model Sales and Marketing Independently
Sales and marketing are major growth expenses for many CRM software companies.
Instead of using one large percentage of revenue, consider modeling important drivers separately.
For example:
Marketing Spend
- Advertising
- Content
- Events
- Software
- Agencies
Sales Spend
- Sales salaries
- Commissions
- Sales tools
- Lead-generation expenses
This makes CAC analysis more meaningful because the business can see where acquisition spending is actually coming from.
15. Payroll Can Become the Largest Expense
A growing software company often adds employees before the revenue impact of those employees becomes visible.
Your model should therefore include headcount assumptions.
A simple structure might include:
| Role | Employees | Monthly Cost Per Employee | Monthly Payroll |
|---|---|---|---|
| Developers | 5 | $7,000 | $35,000 |
| Sales | 3 | $5,000 | $15,000 |
| Marketing | 2 | $5,500 | $11,000 |
| Operations | 1 | $6,000 | $6,000 |
The model can then increase headcount based on planned growth.
For example, additional sales employees might be added when the customer base reaches a certain threshold.
16. Add the Remaining Operating Expenses
A complete model should account for costs outside product development and acquisition.
Potential operating expenses include:
- Office expenses
- Insurance
- Legal services
- Accounting
- Software subscriptions
- Professional services
- Travel
- Administrative expenses
- Customer support
Do not make the model artificially attractive by excluding small recurring expenses.
Individually, these costs may look insignificant. Together, they can materially affect cash flow.
17. Build the Profit and Loss Statement
Once revenue and expenses are modeled, connect them into a profit and loss statement.
A simplified structure is:
Revenue
− Cost of Goods Sold
= Gross Profit
− Sales and Marketing
− Product Development
− Payroll
− General and Administrative Expenses
= Operating Profit
The exact accounting treatment can vary depending on the business and modeling purpose, but the structure should make the company’s economic drivers easy to understand.
18. Do Not Confuse Profit With Cash Flow
A profitable business can still experience cash pressure.
That is why the Excel model should include a cash-flow section.
Track:
- Beginning cash
- Cash collected
- Operating expenses paid
- Capital expenditures
- Financing
- Ending cash
For a subscription business, billing terms also matter.
Annual customers may pay upfront, while monthly customers generate cash over time.
That difference can affect the company’s cash position even when revenue recognition follows a different accounting treatment.
19. Add a Break-Even Analysis
Break-even analysis shows when the business can cover its operating costs.
At a simplified level:
Break-Even Revenue = Fixed Costs ÷ Contribution Margin
The exact calculation depends on how variable costs are modeled.
For a CRM SaaS business, it can also be useful to convert the break-even point into customers.
For example:
Break-Even Customers = Required Contribution ÷ Contribution Per Customer
This turns an abstract financial calculation into a business target.
Instead of saying “we need to become profitable,” management can ask:
How many active customers do we need to support the current cost structure?
20. Track Burn Rate and Runway
Early-stage software businesses may operate at a loss while investing in growth.
In that situation, cash burn becomes an important metric.
A simple monthly burn calculation can be:
Cash Burn = Cash Outflows − Cash Inflows
Runway can then be estimated as:
Runway = Available Cash ÷ Monthly Net Burn
This is a simplified calculation and should be adjusted when burn changes significantly from month to month.
A better Excel model can calculate runway dynamically based on the projected cash balance.
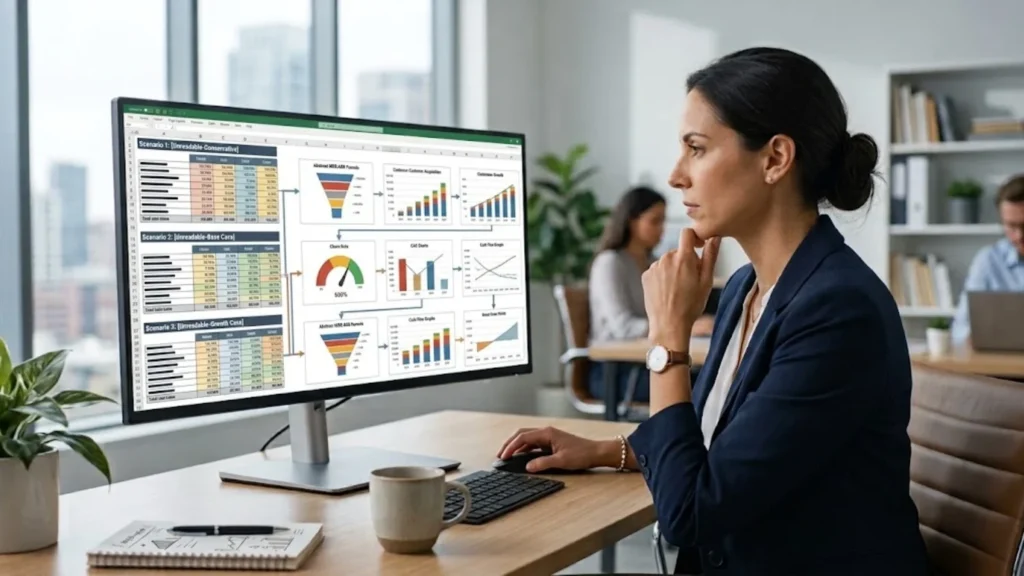
21. Build Scenarios Instead of One Forecast
One forecast is rarely enough.
Create at least three scenarios:
Conservative
Lower customer acquisition, higher churn, and slower revenue growth.
Base Case
The most realistic operating assumptions.
Growth Case
Higher acquisition, stronger conversion, better retention, or improved customer expansion.
The purpose is not to make the growth scenario look impressive.
The purpose is to understand how the business behaves under different assumptions.
22. Use Sensitivity Analysis to Find Dangerous Assumptions
Scenario analysis changes several assumptions at once.
Sensitivity analysis can focus on one variable.
For example, test:
- 1% churn
- 2% churn
- 3% churn
- 4% churn
Then observe the effect on customers, MRR, ARR, profit, and cash.
You can perform similar tests with:
- CAC
- Pricing
- Conversion rate
- Payroll
- Infrastructure cost
This helps identify which assumptions deserve the most attention.
23. Consider Cohort Behavior When the Business Gets Larger
A simple customer model treats all customers similarly.
A more advanced model can group customers by acquisition month or quarter.
For example:
- January cohort
- February cohort
- March cohort
- April cohort
You can then track retention and revenue for each group.
Cohort analysis can reveal whether newer customers are behaving differently from older customers.
That can make the financial model considerably more useful as the business grows.
24. Valuation Should Come After the Operating Model
Valuation is tempting to put at the top of a SaaS financial model.
It usually makes more sense to build it after the operating assumptions are established.
Revenue, growth, retention, margins, and cash requirements should drive the valuation discussion.
Depending on the purpose of the model, you might eventually examine:
- Revenue multiples
- ARR multiples
- Discounted cash flow
- Comparable-company assumptions
The exact valuation approach depends on the business stage and purpose of the model.
The important principle is simple:
Do not use valuation assumptions to hide weaknesses in the underlying operating model.
25. Structure the Excel Workbook Around the Business Logic
A practical workbook might use separate sheets such as:
Sheet 1: Assumptions
Central location for:
- Pricing
- Churn
- Conversion
- CAC
- Headcount
- Salaries
- Infrastructure costs
- Growth assumptions
Sheet 2: Customers
Monthly customer movement and retention.
Sheet 3: Revenue
MRR, ARR, plan mix, expansion, and other revenue.
Sheet 4: Costs
COGS, payroll, sales, marketing, development, and overhead.
Sheet 5: Profit and Loss
Monthly and annual financial statements.
Sheet 6: Cash Flow
Cash inflows, outflows, burn, and ending cash.
Sheet 7: Scenarios
Conservative, base, and growth assumptions.
Sheet 8: Dashboard
Key metrics and charts for management.
This structure makes the workbook easier to audit and update.
26. Keep Assumptions Separate From Formulas
One of the simplest ways to make an Excel financial model easier to maintain is to separate assumptions from calculations.
Instead of entering a churn rate directly into multiple formulas, store it in one assumption cell.
Then reference that cell throughout the workbook.
For example:
Monthly Churn Rate = 2%
The customer model references the assumption.
If the assumption changes to 3%, the dependent calculations update automatically.
This makes scenario testing much easier.
27. Use Monthly Modeling Before Annual Summaries
Annual forecasts can hide important changes.
A CRM software business can grow rapidly during one quarter and slow considerably during another.
Monthly modeling makes it possible to observe:
- Customer additions
- Churn
- MRR growth
- Cash burn
- Hiring
- Marketing expenditure
- Break-even progress
Annual totals can then be calculated from the monthly model.
For an early-stage or rapidly changing software company, this is generally more informative than starting with annual totals.
28. Connect the Financial Model to Real Software Economics
The financial model should ultimately reflect the economics of the actual CRM product.
That means product assumptions should be grounded in realistic software capabilities, pricing structures, customer usage, and operating requirements.
When you need to understand how CRM products are structured at the software level, our CRM software comparison provides useful product-level context.
The financial model can then translate those business assumptions into revenue and cost projections.
29. Avoid These Common Financial-Modeling Mistakes
Hard-Coding Everything
Hard-coded numbers make the model difficult to change.
Assuming Constant Growth
Real businesses rarely grow at exactly the same rate every month.
Ignoring Churn
Subscription revenue cannot be modeled realistically without customer retention assumptions.
Treating Revenue as Cash
Revenue recognition and cash collection are not always identical.
Forgetting Hiring Costs
Headcount growth can consume cash quickly.
Using Unrealistic CAC
Acquisition costs should reflect actual sales and marketing spending.
Mixing Fixed and Variable Costs
The model becomes harder to interpret when cost behavior is unclear.
Building Only a Best-Case Forecast
A forecast is more useful when management can see downside scenarios.
30. Connect the Model to the Business Decision
An Excel model is useful only when someone can make a better decision from it.
For example, the model might answer:
- Can the business afford to hire two more developers?
- How many customers are required to break even?
- What happens if churn rises?
- Can marketing spend increase safely?
- How much cash is needed to reach the next growth stage?
- Which pricing plan produces the strongest economics?
- How long can the company operate under the current burn rate?
These are better questions than simply asking what next year’s revenue will be.
31. Use the CRM Business Strategy as the Starting Point
The financial model should support the broader business strategy rather than exist as a disconnected spreadsheet.
If you are evaluating the CRM market itself, first understand how businesses use CRM products and what capabilities different products offer. Our guide to choosing the right small-business CRM provides broader context around CRM business requirements and selection.
The financial model then moves the discussion in a different direction: what those software economics could mean for a CRM business’s revenue, costs, cash flow, and growth.
32. The Bottom Line
A strong small business CRM software Excel financial model should do more than calculate projected revenue.
It should explain how customers are acquired, how they generate recurring revenue, how many leave, how much it costs to acquire them, how much gross profit they generate, and how those economics interact with payroll, infrastructure, product development, and operating expenses.
The most useful model is not necessarily the most complicated one.
It is the model where every important number has a clear business reason behind it.
Start with assumptions. Build the customer engine. Connect customers to revenue. Add direct costs and operating expenses. Then build cash flow, break-even analysis, scenarios, and sensitivity testing.
Once those pieces work together, Excel becomes more than a spreadsheet.
It becomes a practical decision-making tool for understanding whether the CRM software business can grow efficiently, remain financially sustainable, and reach its next stage with enough cash to support the plan.
admin
Practical business guides, useful tools, and technology insights from BusinessNexa.
Work smarter with practical business tools.
Explore useful calculators, guides and tools for modern businesses.