Revenue and Profit Difference: Examples and Key Differences
Revenue and profit are two essential measures of business performance, but they tell different stories. Revenue represents the income a […]

Revenue and profit are two essential measures of business performance, but they tell different stories. Revenue represents the income a business earns from its ordinary activities before expenses are deducted. Profit shows what remains after the relevant costs and expenses have been accounted for.
A company can generate thousands of dollars in sales and still struggle to make a profit. On the other hand, a business with lower revenue may perform well financially if it controls costs and earns a healthy margin on its products or services.
Understanding the revenue and profit difference helps business owners evaluate sales, set prices, manage expenses, and make more informed financial decisions. Instead of focusing on sales alone, they can see whether their business activity is actually producing a sustainable return.
What Is Revenue in Business?
Revenue is the amount a business earns from selling products or providing services during a specific accounting period. Depending on the accounting method and transaction, revenue is generally recognized when it is earned, not necessarily when the customer pays.
Consider a consulting business that completes 40 projects at $1,000 each during one month.
Revenue = Number of projects × Price per project
Revenue = 40 × $1,000 = $40,000
The business has generated $40,000 in revenue before deducting employee wages, software subscriptions, marketing expenses, rent, taxes, and other applicable costs.
Common sources of revenue include:
- Product sales
- Consulting and professional services
- Subscription fees
- Project-based payments
- Other ordinary business activities
Depending on how sales are reported, discounts, refunds, returns, and allowances may reduce gross sales to calculate net revenue.
Revenue helps business owners measure sales activity, track demand, and evaluate growth. However, it does not reveal how much money the business retains after covering its expenses.
What Is Profit in Business?
Profit is the amount remaining after a business subtracts the relevant costs and expenses from its revenue. The figure depends on which profit measure is being used.
Gross profit is revenue minus the cost of goods sold or the direct costs associated with providing a service.
Operating profit reflects what remains after operating expenses are deducted from gross profit. The precise calculation depends on the business’s income statement and accounting presentation.
Net profit is the amount remaining after the expenses and other items included in the net income calculation, including applicable interest and income taxes, have been accounted for.
These measures should not be treated as interchangeable. Gross profit helps show how much remains after direct costs, operating profit helps evaluate operating performance, and net profit provides a broader view of the final financial result.
For example, a retailer might earn $40,000 in revenue and spend $16,000 purchasing the products it sells. Its gross profit would be $24,000. Once operating expenses and other applicable costs are deducted, its net profit will be lower.
Revenue and Profit Difference at a Glance
| Business measure | Revenue | Profit |
|---|---|---|
| What it measures | Income earned from business activities | Amount remaining after relevant costs |
| Are expenses deducted? | Not from the revenue figure itself | Yes, depending on the profit measure |
| Main purpose | Track sales activity and demand | Evaluate profitability |
| Can the business still lose money? | Yes, even with substantial revenue | A net loss occurs when applicable expenses exceed revenue |
| Useful for | Sales analysis and growth tracking | Pricing, cost control, and financial decisions |
The central distinction is straightforward: revenue measures what a business earns from its sales, while profit measures what remains after the relevant deductions.
To better understand how these financial terms differ, explore our guide to understanding revenue, income, and profit.
A Step-by-Step Example of Revenue and Profit Difference
Imagine a small furniture business that generates $80,000 in revenue during one month. Its financial statement shows the following results.
| Financial item | Amount |
|---|---|
| Revenue | $80,000 |
| Cost of goods sold | $32,000 |
| Gross profit | $48,000 |
| Operating expenses | $30,000 |
| Operating profit | $18,000 |
| Interest and other expenses | $2,000 |
| Income before taxes | $16,000 |
| Income tax expense | $3,200 |
| Net profit | $12,800 |
These figures are illustrative. Actual financial statements may classify or present certain items differently.
The business generated $80,000 in revenue, but it did not keep that entire amount. After accounting for the costs and expenses listed above, it earned $12,800 in net profit.
The example also shows why the type of profit matters. Gross profit was $48,000, operating profit was $18,000, and net profit was $12,800. Each measure reveals a different stage of the company’s financial performance.
For a closer look at how the final profit figure relates to sales, see our explanation of revenue compared with net income.
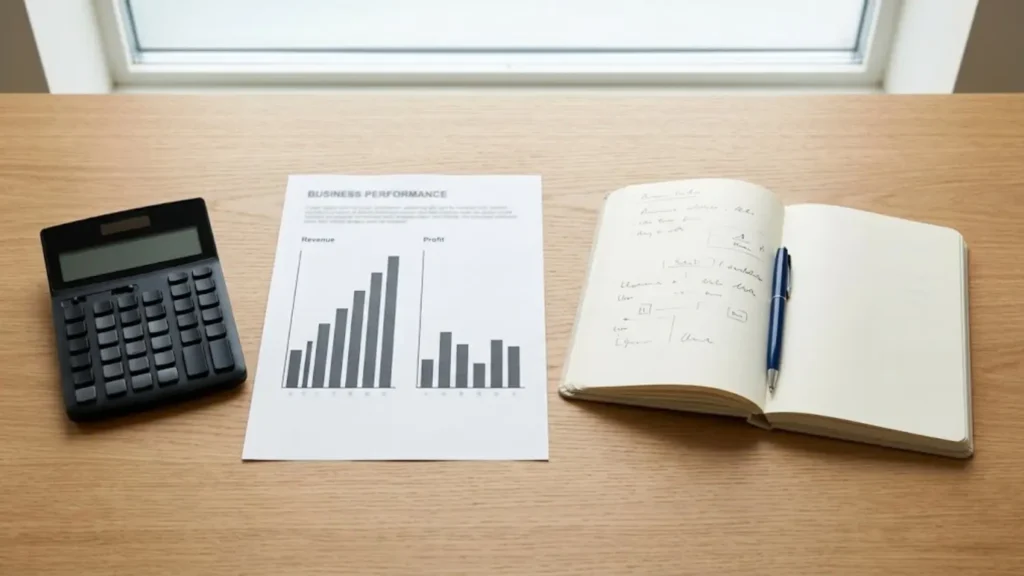
Why Higher Revenue Does Not Always Mean Higher Profit
Increasing sales can help a business grow, but additional revenue does not automatically produce better financial results. Profit may decline if the costs associated with generating those sales rise faster than revenue.
Rising Direct Costs
A business may receive more orders while paying more for materials, inventory, shipping, or contractors. If direct costs rise faster than sales, gross profit margins can shrink.
For instance, a company might increase its monthly sales from $50,000 to $70,000. If the cost of fulfilling those sales increases disproportionately, the additional revenue may generate only a small increase in gross profit.
Higher Operating Expenses
Expansion often brings new expenses, such as additional employees, advertising, software, insurance, and office space. These costs may support future growth, but business owners need to evaluate whether the resulting sales justify the spending.
Discounting and Pricing Pressure
Discounts can attract customers and increase order volume, but lower prices reduce the amount earned on each sale. If the remaining amount cannot adequately cover costs, selling more products may not improve profitability.
Interest and Taxes
A business may generate positive operating profit but retain less after interest expenses and applicable income taxes. That is why operating performance and the final profit figure should be reviewed separately.
Delayed Customer Payments
Revenue and profit are not the same as cash flow. A business may recognize revenue from a credit sale before receiving payment. Even a profitable company can experience cash shortages if customers pay late or significant bills fall due before collections arrive.
How to Calculate Profit From Revenue
The basic formula is:
Profit = Revenue − Relevant costs and expenses
The specific calculation depends on the measure you want to find.
For the furniture business, the figures are:
- Revenue: $80,000
- Total costs and expenses in the example: $67,200
- Net profit: $12,800
Therefore:
Net profit = $80,000 − $67,200 = $12,800
The distinction between the different profit measures is important. Subtracting only the cost of goods sold gives gross profit. Deducting operating expenses as well helps calculate operating profit. Further deductions, including applicable interest and taxes, contribute to the net profit calculation.
When reviewing financial statements, always confirm which costs have been deducted before interpreting the reported profit.
How Profit Margin Adds More Context
Revenue and profit are dollar amounts, while profit margin expresses profit as a percentage of revenue. This percentage makes it easier to evaluate profitability across periods with different sales totals.
The net profit margin formula is:
Net profit margin = (Net profit ÷ Revenue) × 100
Using the furniture business example:
Net profit margin = ($12,800 ÷ $80,000) × 100 = 16%
The business retained $0.16 in net profit for every dollar of revenue during the period.
Now imagine revenue rises to $100,000 while net profit remains at $12,800. The net profit margin falls to 12.8%.
Although sales have increased, the company is keeping a smaller percentage of its revenue as profit. This is why business owners should assess revenue, profit, and margins together rather than relying on sales growth alone.
Which Figure Should a Business Owner Monitor?
The most useful measure depends on the decision being made. Revenue and profit provide complementary information, so business owners should review both.
- To evaluate sales growth: Track revenue over time and consider changes in prices, discounts, returns, and sales volume.
- To review product pricing: Compare selling prices with direct costs and gross profit.
- To manage operating costs: Monitor operating expenses and operating profit.
- To assess overall profitability: Review net profit and net profit margin.
- To manage upcoming payments: Check cash flow, outstanding invoices, and financial obligations.
If revenue is increasing but profit is declining, investigate whether costs are rising, prices are too low, or some products and services are less profitable than expected. If revenue remains steady while profit improves, the business may be benefiting from better pricing or stronger expense management.
The right interpretation depends on the company’s business model, industry, stage of growth, and accounting practices.
Common Mistakes When Comparing Revenue and Profit
Assuming revenue is money the business keeps. Revenue is recorded before the relevant expenses are deducted. It should not be treated as the amount available to spend.
Using gross profit and net profit interchangeably. These measures reflect different stages of the calculation. Always identify the specific profit figure being discussed.
Assuming higher sales guarantee better results. Sales growth can coincide with declining margins when costs increase too quickly.
Confusing profit with cash in the bank. A business can report a profit while waiting for customers to pay outstanding invoices. Cash-flow planning remains essential.
Comparing businesses without considering their models. A retailer and a consulting firm may have very different cost structures. Their revenue totals alone do not establish which business is more profitable or financially efficient.
A more reliable assessment combines revenue, the appropriate profit measures, profit margins, and cash-flow information.
Final Thoughts
The main revenue and profit difference is that revenue measures income earned from business activities, while profit reflects what remains after the relevant costs and expenses have been deducted.
Both figures are necessary for understanding financial performance. Revenue helps business owners assess sales activity and demand. Profit reveals whether those sales are translating into a positive financial result, while profit margin shows how much of each revenue dollar the business retains.
By tracking these measures together and reviewing the costs behind them, business owners can identify profitable growth, manage expenses, and make better decisions about pricing and operations.
admin
Practical business guides, useful tools, and technology insights from BusinessNexa.
Work smarter with practical business tools.
Explore useful calculators, guides and tools for modern businesses.