Whole-Farm Revenue Protection: Coverage and Eligibility
A diversified farm can generate income from several crops, livestock products, specialty commodities, or different markets. Managing all of that […]
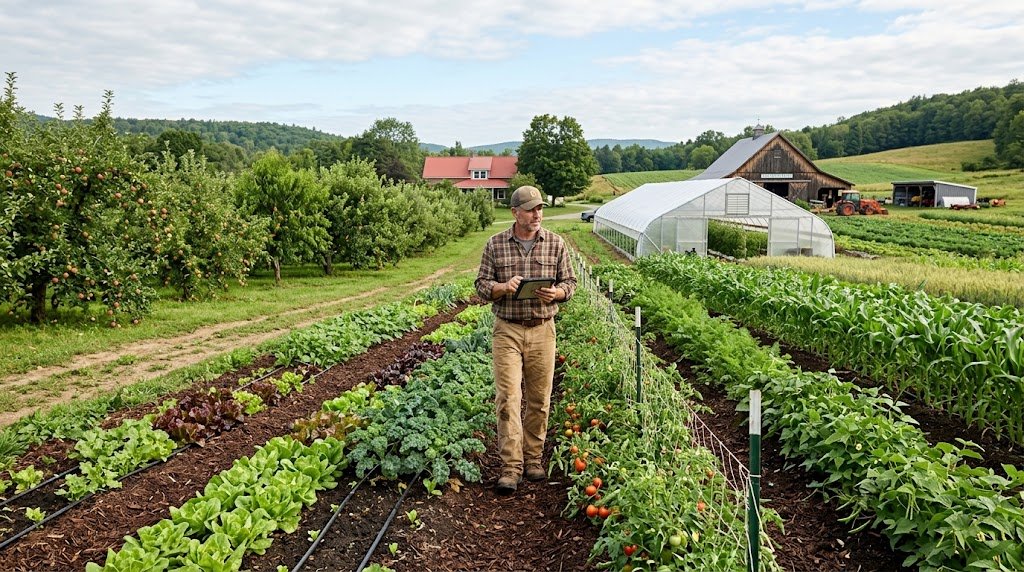

A diversified farm can generate income from several crops, livestock products, specialty commodities, or different markets. Managing all of that revenue can be more complicated than insuring one crop at a time.
Whole-Farm Revenue Protection (WFRP) is a federal crop insurance program designed to provide revenue protection for eligible commodities produced or purchased for resale during the insurance period under one policy.
The program can be particularly relevant to diversified farms and operations selling through specialty, local, regional, direct, or farm-identity-preserved markets. USDA’s Risk Management Agency describes WFRP as a program designed for highly diverse farms and states that it is available nationwide.
What Is Whole-Farm Revenue Protection?
Whole-Farm Revenue Protection is a crop insurance plan that protects eligible farm revenue under one policy rather than focusing exclusively on a single crop.
The program can consider revenue from multiple eligible commodities, subject to its rules and limitations.
That can make WFRP different from crop-specific insurance products.
For example, a diversified farm may grow vegetables, fruit, and other eligible agricultural products. Instead of evaluating each source of revenue completely separately, WFRP provides a framework for considering qualifying farm revenue under one policy.
However, WFRP does not automatically cover every source of business income, and eligibility requirements still apply.
How Does WFRP Work?
The amount of revenue a farm can protect is generally based on the lower of the revenue expected under the current-year farm plan or the farm’s five-year average historical income adjusted for growth, subject to the policy’s rules.
The producer then selects an available coverage level.
For the 2026 WFRP plan, RMA lists coverage levels from 50% to 90% in 5-percentage-point increments.
The resulting guarantee is not the same as a farm’s total sales or profit. The policy determines which revenue is eligible and how the calculation is made.
Which Farms May Be a Good Fit?
WFRP may be worth investigating for farms that:
- Produce several eligible commodities
- Sell through local or regional markets
- Use direct-to-consumer or specialty markets
- Produce specialty crops
- Have eligible livestock or animal-product revenue
- Want to manage revenue risk across the farm rather than one commodity
RMA specifically says WFRP was developed for highly diverse farms, including operations producing specialty crops and farms selling through direct, local, regional, or farm-identity-preserved markets.
That does not mean every diversified farm automatically qualifies.
WFRP Eligibility Requirements
WFRP has specific eligibility and coverage limits.
For 2026, RMA states that:
- Total WFRP coverage must be $17 million or less at the sales closing date.
- Expected covered revenue from animals and animal products, excluding aquaculture commodities, is subject to a $2 million limit.
- Expected covered revenue from nursery and greenhouse products, excluding aquaculture commodities, is subject to a $2 million limit.
- Certain farms must meet minimum commodity-count requirements to qualify.
These rules are important because a farm can be diversified and still fail to meet the program’s requirements.
Always verify the current policy for the applicable insurance year before making a decision.
What Coverage Levels Are Available?
For the 2026 plan, WFRP provides coverage levels from 50% through 90%, increasing in five-percentage-point increments.
The selected coverage level affects both the amount of revenue protected and the premium.
A higher coverage percentage can provide a larger revenue guarantee, but that does not automatically make it the best financial choice.
Farmers should compare:
- Expected premium
- Insured revenue
- Coverage level
- Farm cash flow
- Potential loss exposure
- Other crop insurance already in place
What Records Does WFRP Require?
WFRP relies heavily on financial and farm records.
RMA explains that federal farm income tax returns are used to establish historical revenue, with specific adjustments made to determine allowable revenue.
Depending on the farm, documentation may include:
- Federal farm tax returns
- Farm operation reports
- Expected revenue information
- Marketing records
- Inventory information
- Records related to individual crop insurance policies
- Organic certification where applicable
- Other documents requested by the insurance provider
Direct-market farms should pay particular attention to sales and marketing records.
Keeping organized records throughout the year can make the application and reporting process much easier.
WFRP vs. Revenue Protection
WFRP and Revenue Protection both address revenue risk, but they are designed differently.
Revenue Protection generally focuses on an individual insured crop and uses crop-specific yield and price provisions.
WFRP evaluates eligible revenue across the farm under its own program rules.
| Feature | Revenue Protection | Whole-Farm Revenue Protection |
|---|---|---|
| Main focus | Individual insured crop | Eligible farm revenue |
| Revenue basis | Crop-specific policy calculation | Farm-level revenue calculation |
| Diversified operations | May require separate crop policies | Designed for qualifying diversified farms |
| Coverage | Depends on crop and location | Available nationwide under WFRP rules |
These differences mean that farmers should compare the policies based on their actual operation rather than assuming one is universally better.
If you want to understand the crop-specific approach first, read our guide to Revenue Protection crop insurance.
Farmers interested in the importance of historical revenue records can also read our guide to Actual Revenue History and crop insurance.
How Much Does WFRP Cost?
There is no universal WFRP premium.
The cost depends on factors such as the farm’s approved revenue, selected coverage level, policy provisions, and applicable subsidy.
For 2026, RMA lists different subsidy percentages by coverage level, so farmers should not assume that every coverage level receives the same premium subsidy.
The best way to determine the actual cost is to request a current quote from an approved crop insurance agent.
Important WFRP Deadlines
Sales closing dates depend on the farm’s tax-year structure and applicable county requirements.
RMA’s 2026 guidance explains different sales closing dates for calendar-year and fiscal-year filers. For some operations, the applicable date falls in January, February, or March, while certain later fiscal-year filers may have a November 20 deadline.
Because deadlines can determine whether coverage is available, farmers should confirm the date for their specific operation well before the deadline.
Questions to Ask Before Buying WFRP
Before purchasing coverage, ask:
- Does my farm meet the current WFRP eligibility requirements?
- Which sources of revenue qualify?
- Which historical tax records are required?
- How will my approved revenue be calculated?
- Which coverage levels are available?
- What will the premium be?
- How will my existing crop insurance affect WFRP?
- What is my exact sales closing date?
- What records must I submit during the insurance period?
Getting clear answers before purchasing can make the policy much easier to understand.
Frequently Asked Questions
What does Whole-Farm Revenue Protection cover?
WFRP protects eligible farm revenue under the policy’s terms. It can cover qualifying commodities produced or purchased for resale during the insurance period.
What is the maximum WFRP coverage?
For the 2026 plan, RMA states that total WFRP coverage must be $17 million or less at the sales closing date. Additional revenue limits apply to certain categories.
What coverage levels are available?
For 2026, WFRP coverage levels range from 50% to 90% in 5-percentage-point increments.
Is WFRP available nationwide?
RMA states that WFRP is available in all 50 states and all counties within each state.
Is WFRP suitable for every farm?
No. The program is particularly designed for diverse operations, but eligibility requirements, revenue limits, commodity rules, and recordkeeping requirements still apply.
Conclusion
Whole-Farm Revenue Protection can provide a useful risk-management option for qualifying farms that generate revenue from multiple eligible commodities.
Its biggest advantage is the ability to evaluate eligible farm revenue under one policy rather than treating every commodity as an isolated business risk. However, the program has detailed rules around revenue history, coverage levels, eligibility, records, and deadlines.
Before purchasing WFRP, review the current USDA RMA requirements and work with an approved crop insurance agent to determine whether the policy fits your operation.
admin
Practical business guides, useful tools, and technology insights from BusinessNexa.
Work smarter with practical business tools.
Explore useful calculators, guides and tools for modern businesses.