Company Fundamentals: What They Are and How to Evaluate a Business
A company’s revenue, profit, or stock price can give you a quick snapshot, but none of those figures tells the […]
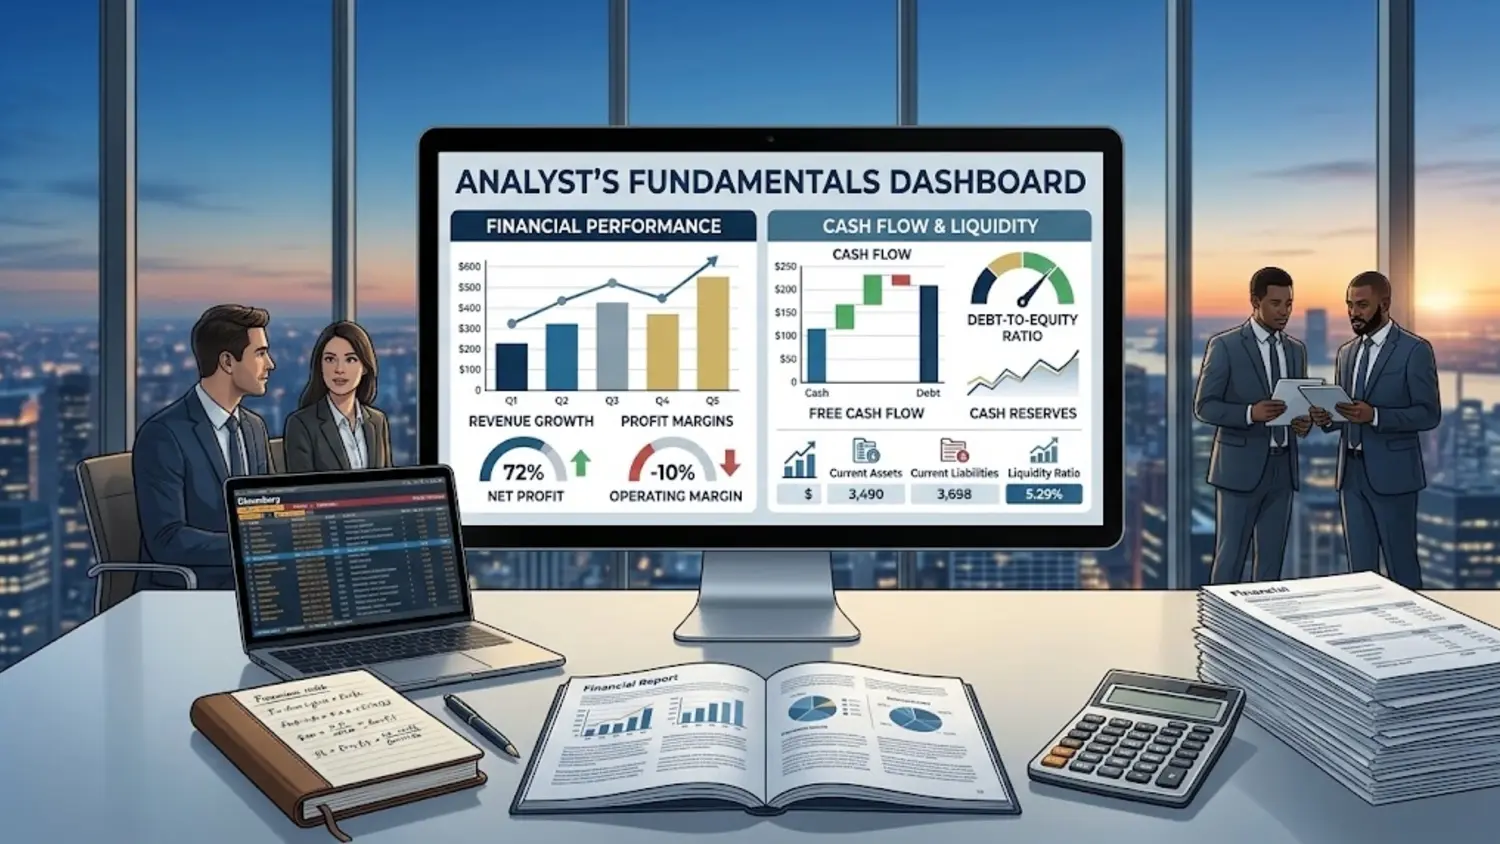

A company’s revenue, profit, or stock price can give you a quick snapshot, but none of those figures tells the whole story.
To understand the underlying health of a business, you need to look at several financial and operational signals together. These are commonly referred to as company fundamentals.
Company fundamentals can include:
- Revenue and revenue growth
- Gross and operating margins
- Cash flow
- Debt
- Liquidity
- Assets and liabilities
- Business model
- Competitive position
- Management and capital allocation
The goal is not to find one perfect number. It is to understand how the pieces connect and whether the business is improving, weakening, or changing direction.
What Are Company Fundamentals?
Company fundamentals are the underlying financial, operational, and qualitative characteristics used to evaluate a business.
Some are directly measurable.
For example:
- Revenue
- Operating income
- Cash
- Debt
- Assets
- Liabilities
Others require judgment.
Examples include:
- Competitive advantages
- Customer loyalty
- Business quality
- Management decisions
- Industry conditions
That is why fundamental analysis is broader than simply checking whether a company’s revenue went up.
Start With the Three Financial Statements
A practical analysis usually begins with the three major financial statements:
- Income statement
- Balance sheet
- Cash flow statement
Each answers a different question.
Income Statement
The income statement shows financial performance over a reporting period.
It can include:
- Revenue
- Cost of sales
- Gross profit
- Operating expenses
- Operating income
- Interest
- Taxes
- Net income
Balance Sheet
The balance sheet shows a company’s financial position at a particular date.
It includes:
- Assets
- Liabilities
- Shareholders’ equity
This statement can help you understand liquidity, leverage, and the resources supporting the business.
Cash Flow Statement
The cash flow statement tracks cash inflows and outflows associated with operating, investing, and financing activities.
This matters because accounting profit and cash generation are not necessarily identical.
For readers who want to see how financial statements are analyzed in practice, Corporate Finance Institute’s financial-statement analysis lesson covers the income statement, balance sheet, cash flow statement, ratio analysis, and trend analysis.
Recommended YouTube Resource
1. Revenue and Revenue Growth
Revenue is one of the first figures to examine.
But don’t stop at:
Did revenue increase?
Ask:
Why did revenue increase?
Growth could come from:
- Higher prices
- More customers
- More units sold
- New products
- Acquisitions
- Expansion into new markets
- Currency movements
A company generating growth through acquisitions may have a very different underlying growth profile from one growing through existing customers.
Revenue growth is therefore a starting point, not a complete assessment.
2. Gross Profit and Gross Margin
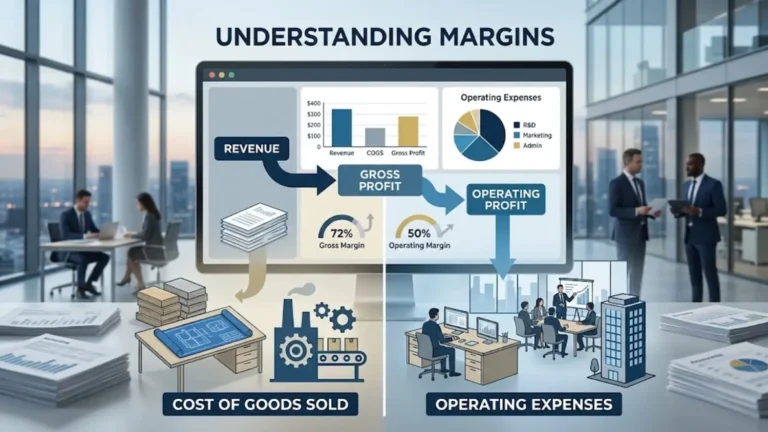
Gross profit shows what remains after applicable cost of goods sold or cost of revenue is deducted from revenue.
Gross Profit = Revenue − COGS
Gross margin is:
Gross Margin = Gross Profit ÷ Revenue × 100
Suppose:
- Revenue = $1 million
- COGS = $600,000
Gross profit is:
$1,000,000 − $600,000 = $400,000
Gross margin is:
$400,000 ÷ $1,000,000 × 100 = 40%
Gross margin can provide insight into pricing, direct costs, product mix, and the economics of what the business sells.
For a deeper comparison of profitability measures, see our guide to gross profit and operating profit.
3. Operating Profit and Operating Margin
Operating profit goes beyond gross profit by accounting for operating expenses.
A simplified operating-margin calculation is:
Operating Margin = Operating Income ÷ Revenue × 100
If operating income is $150,000 on $1 million of revenue:
$150,000 ÷ $1,000,000 × 100 = 15%
Operating margin can help show how effectively the company converts revenue into operating earnings.
A declining margin may reflect higher expenses, pricing pressure, changes in product mix, or deliberate investment in growth.
The number itself matters, but understanding the reason behind the change matters more.
4. Cash Flow
Cash flow deserves close attention because accounting profit does not automatically mean the company generated the same amount of cash.
Cash can be tied up in:
- Accounts receivable
- Inventory
- Capital investments
- Working capital
- Other business activities
Look at operating cash flow over several periods and compare it with reported earnings.
A difference does not automatically indicate a problem. It is a reason to investigate what is driving the difference.
5. Free Cash Flow
A commonly used simplified calculation is:
Free Cash Flow = Operating Cash Flow − Capital Expenditures
Free cash flow can show how much cash remains after capital investments.
Depending on the business, that cash might support:
- Debt repayment
- Acquisitions
- Dividends
- Share repurchases
- Expansion
- Additional investment
The appropriate amount of free cash flow depends heavily on the company’s industry and stage of development.
6. Debt and Leverage
Debt is not automatically a weakness.
Borrowing can help a company finance expansion, acquire assets, or invest in growth.
The more important question is whether the business can manage its obligations.
Review:
- Total debt
- Net debt
- Debt-to-equity
- Interest coverage
- Debt maturities
- Cash balances
A company with stable and predictable cash flows may be able to support more debt than one whose revenue fluctuates heavily.
7. Liquidity
Liquidity refers to the ability to meet short-term obligations.
A basic working-capital calculation is:
Working Capital = Current Assets − Current Liabilities
Current assets can include cash, receivables, and inventory.
Current liabilities can include accounts payable and other short-term obligations.
Liquidity matters because a business can be profitable while still experiencing financial pressure if it cannot meet obligations when they become due.
8. Earnings Per Share
For public companies, earnings per share, or EPS, provides another useful perspective.
A simplified formula is:
EPS = Net Income Available to Common Shareholders ÷ Weighted Average Common Shares Outstanding
EPS matters because total earnings and earnings attributable to each share can move differently.
For example, if net income increases but the number of shares also increases substantially, EPS growth may be much smaller than total earnings growth.
9. Return on Equity
Return on equity, or ROE, measures net income relative to shareholders’ equity.
A simplified formula is:
ROE = Net Income ÷ Average Shareholders’ Equity × 100
ROE can help with comparisons, but it should not be viewed in isolation.
Debt and financial leverage can influence ROE, so a high ROE does not automatically mean the company has superior operating performance.
10. Understand the Business Model
Financial numbers become much easier to interpret when you understand how the company makes money.
Ask:
- What does it sell?
- Who buys it?
- How does revenue get generated?
- What are the biggest costs?
- Is revenue recurring?
- How easy is it for customers to switch?
- What drives repeat purchases?
A company can report strong financial results today while facing structural challenges that have not yet appeared clearly in the latest numbers.
11. Examine the Competitive Position
Competitive advantages can influence whether financial performance is sustainable.
Potential advantages include:
- Strong brands
- Switching costs
- Distribution networks
- Proprietary technology
- Network effects
- Economies of scale
- Specialized expertise
But an advantage should be tested rather than assumed.
Ask whether it actually helps the company retain customers, protect pricing, maintain margins, or defend market share.
12. Evaluate Management and Capital Allocation
Management makes decisions about how the company uses its resources.
Review decisions involving:
- Acquisitions
- Debt repayment
- Expansion
- Research and development
- Dividends
- Share repurchases
- New projects
A company can generate strong cash flow and still make poor capital-allocation decisions.
Likewise, temporarily lower earnings can sometimes reflect deliberate investment in future growth.
A Practical Process for Evaluating Company Fundamentals
You don’t need to analyze every metric simultaneously.
A practical process is:
Step 1: Understand the Business
Explain what the company does and how it makes money.
Step 2: Review Revenue Trends
Look at multiple reporting periods and identify the main drivers of growth.
Step 3: Examine Margins
Review gross and operating margins and investigate meaningful changes.
Step 4: Study Cash Flow
Compare operating cash flow with reported earnings.
Step 5: Review Debt
Consider both the amount of debt and the company’s ability to service it.
Step 6: Check Liquidity
Review cash, current assets, and short-term obligations.
Step 7: Compare With Relevant Peers
Peer comparisons can provide useful context for financial ratios and margins.
Step 8: Investigate Contradictions
Pay attention when:
- Revenue rises but cash flow falls
- Profit increases but margins shrink
- Debt grows faster than earnings
- EPS grows much more slowly than net income
A contradiction does not automatically mean something is wrong.
It tells you where to investigate further.
A Simple Company Fundamentals Example
Consider two fictional businesses:
| Metric | Company A | Company B |
|---|---|---|
| Revenue growth | 12% | 6% |
| Gross margin | 40% | 48% |
| Operating margin | 17% | 14% |
| Operating cash flow | $70M | $90M |
| Net debt | $150M | $50M |
Company A has stronger revenue growth and a higher operating margin.
Company B has a higher gross margin, higher operating cash flow in this simplified example, and substantially less net debt.
Which company has stronger fundamentals?
You cannot answer that from the table alone.
You would need to understand:
- Why Company A is growing faster
- Whether Company B’s cash flow is sustainable
- Why their gross margins differ
- How much debt each business can support
- What industries they operate in
- How management is allocating capital
This is why fundamental analysis is about relationships, trends, and context, rather than finding one winning number.
Common Mistakes When Analyzing Fundamentals
Looking Only at Revenue
Revenue growth does not guarantee profitable growth.
Looking Only at Profit
Profit does not necessarily tell you how much cash the company generated.
Ignoring Debt
Debt can materially affect financial risk.
Comparing Unrelated Industries
Financial ratios can mean very different things across industries.
Using One Reporting Period
A single reporting period may contain unusual or temporary conditions.
Ignoring Share Count
Share dilution can affect per-share results.
Confusing Fundamentals With Valuation
Company fundamentals describe the underlying business.
Valuation asks how much investors are paying for that business.
They are related, but they are not the same thing.
Frequently Asked Questions
What are company fundamentals?
Company fundamentals are the financial, operational, and qualitative characteristics used to understand the health and performance of a business.
What are the most important company fundamentals?
Revenue growth, profitability, cash flow, debt, liquidity, balance-sheet strength, business model, competitive position, and management are commonly important areas.
How do you check company fundamentals?
Start with the income statement, balance sheet, and cash flow statement. Then examine financial ratios, debt, cash generation, business quality, and relevant competitors.
Are company fundamentals only financial numbers?
No. Financial data is important, but business model, competition, management, customer relationships, and industry conditions can also matter.
Are company fundamentals the same as stock valuation?
No. Fundamentals describe the underlying business. Valuation considers the price investors are paying relative to the business’s expected results.
Can a company have strong fundamentals but a falling stock price?
Yes. Market expectations, valuation changes, sentiment, interest rates, and other factors can affect a stock price even when the underlying business remains financially healthy.
Final Takeaway
Company fundamentals are best understood as a collection of signals rather than a single score.
Start with revenue and profitability, then examine cash flow, debt, liquidity, and the balance sheet. After that, consider the business model, competitive position, management, and industry.
The strongest analysis doesn’t simply ask whether a number is high or low. It asks why the number is changing, what is driving that change, and whether it is likely to be sustainable.
admin
Practical business guides, useful tools, and technology insights from BusinessNexa.
Work smarter with practical business tools.
Explore useful calculators, guides and tools for modern businesses.