Self-Employed Loans With No Proof of Income: Options to Consider
Getting a loan can be more complicated when you work for yourself and do not receive traditional pay stubs. Freelancers, […]
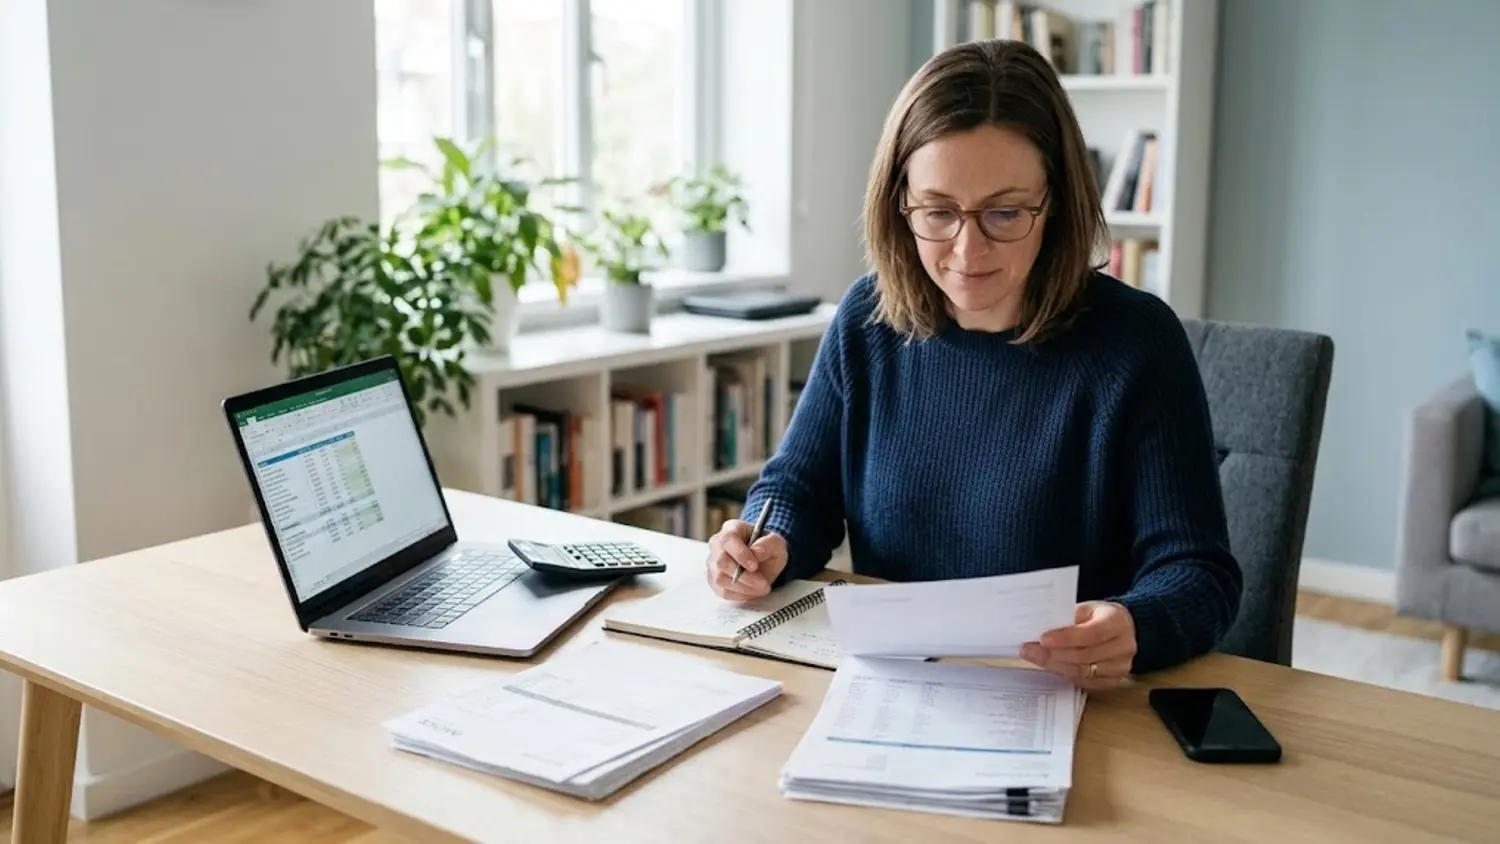

Getting a loan can be more complicated when you work for yourself and do not receive traditional pay stubs. Freelancers, independent contractors, consultants, and small-business owners may have irregular income, multiple clients, seasonal revenue, or different payment schedules.
That is why many people search for self-employed loans with no proof of income.
The good news is that not having a conventional pay stub does not necessarily mean you have no way to demonstrate income. Depending on the lender and loan type, bank statements, invoices, tax records, contracts, payment processor reports, or business financial statements may provide alternative evidence.
However, “no proof of income” should not be interpreted as “no income verification.” A lender still needs some way to determine whether you can repay the debt.
What Does No-Proof-of-Income Financing Mean?
No-proof-of-income financing generally refers to loans marketed toward borrowers who cannot provide conventional employment documents such as pay stubs or employer verification.
The term does not have one standard definition.
One lender may accept bank statements instead of pay stubs. Another may require tax returns. A third may assess business revenue or other financial information.
So before applying, find out what the lender actually means by “no proof of income.”
It could mean:
- No traditional pay stubs
- No employer verification
- Alternative income documentation
- Limited financial paperwork
- Business-revenue-based underwriting
It does not automatically mean:
- No credit check
- No income verification
- No documentation
- Guaranteed approval
- No repayment assessment
Understanding this difference can help you avoid misleading financing offers.
Can Self-Employed People Get a Loan Without Traditional Income Proof?
Possibly.
Self-employed borrowers may qualify for certain personal or business financing when they can demonstrate their ability to repay through alternative financial records.
For example, a freelance consultant may not have a salary statement but could have:
- Regular client payments
- Business bank statements
- Signed contracts
- Invoices
- Tax returns
- Payment processor records
A lender may use some combination of these records to evaluate the application.
The first step is to determine whether you need the money for a personal expense or a business expense. That distinction can affect which financing products are appropriate.
Alternative Ways to Verify Self-Employed Income
Bank Statements
Bank statements can show deposits, payment patterns, and cash flow over time.
A lender may ask for several months of statements or use secure electronic account verification.
However, not every deposit is income. Transfers between accounts, refunds, loan proceeds, and other non-revenue transactions may need to be excluded when assessing actual earnings.
Keeping business transactions organized can make this process easier.
Tax Returns
Tax returns can provide a record of historical income.
Self-employed borrowers may have income that changes from year to year, so a lender may review multiple years or compare tax information with more recent financial activity.
If you operate a business, the lender may ask for personal returns, business returns, or both depending on the business structure and financing product.
Invoices and Client Contracts
Freelancers and service providers can sometimes demonstrate their work through invoices, contracts, purchase orders, and payment histories.
These records can show how the business generates revenue and whether there are continuing customer relationships.
However, an unpaid invoice is not the same as collected income. Future work also does not guarantee future payment.
Profit-and-Loss Statements
A profit-and-loss statement summarizes revenue and expenses over a specific period.
It can help show whether the business is generating enough profit to support another monthly obligation.
Some lenders may accept borrower-prepared financial statements, while others may require supporting documentation or professionally prepared records.
Payment Processor and Marketplace Records
Online businesses and freelancers may receive payments through payment processors or marketplaces.
Transaction reports can provide another way to demonstrate sales activity.
When evaluating these records, a lender may consider refunds, chargebacks, platform fees, and other deductions.
Financing Options for Self-Employed Borrowers
Different financing products suit different situations.
Personal Loans
Some lenders accept self-employed borrowers who can verify income through alternatives to traditional pay stubs.
Depending on the lender, this might include bank statements, tax records, or other accepted documentation.
Personal loans may be suitable for eligible personal expenses, but the lender can still review credit and repayment ability.
Always check the permitted use of the loan before applying.
Business Term Loans
A business term loan provides a lump sum that the borrower repays over a specified period.
It may be useful for:
- Equipment
- Expansion
- Inventory
- Business improvements
- Planned operating expenses
Self-employed business owners may need to provide business financial information and details about existing debt.
If your primary challenge is limited paperwork for business financing, our guide to business financing with limited documentation covers what lenders may actually require.
Business Lines of Credit
A business line of credit provides access to funds up to an approved limit.
It can be useful for businesses with short-term cash-flow gaps, particularly when there is a difference between completing work and receiving customer payments.
However, a credit line should not be treated as permanent income. Draw only what the business can realistically repay.
Invoice Financing
Invoice financing can help businesses that have unpaid customer invoices but need working capital before those invoices are paid.
The business may receive financing against eligible receivables under the lender’s terms.
This option is less useful for businesses that do not invoice customers or primarily receive immediate payment.
Secured Financing
A secured loan uses an asset as collateral.
Depending on the product, that asset could be eligible business equipment, a vehicle, savings, or another accepted asset.
Collateral can affect the lender’s risk assessment, but it does not remove the need for repayment. If the borrower defaults, the lender may have rights to the pledged asset under the agreement.
Personal or Business Financing: Which Is Better?
Self-employed borrowers sometimes treat personal and business loans as interchangeable, but they can have very different requirements and consequences.
| Consideration | Personal financing | Business financing |
|---|---|---|
| Primary purpose | Eligible personal expenses | Eligible business expenses |
| Common evaluation factors | Personal credit and income | Business revenue, cash flow, credit, and owner information |
| Documentation | Personal financial records | Business financial records and formation information |
| Repayment source | Personal finances | Business cash flow, depending on the agreement |
| Potential liability | Generally personal | May include personal guarantee |
The correct option depends on your circumstances and the lender’s terms.
If the money is being used for business expenses, business financing may provide a more appropriate structure. If the expense is personal, using business financing simply because it appears easier may not be appropriate.
How to Improve Your Chances of Approval
Keep Financial Records Organized
Maintain accurate records of revenue, expenses, invoices, and debt payments.
If you operate a business, separating business and personal transactions where appropriate can make income easier to document.
Track Income Over Several Months
Self-employed income can fluctuate significantly.
For example, a freelancer might earn $8,000 in one month and $3,000 the next. Planning a loan payment around the stronger month alone could create problems during slower periods.
Review your average income and expenses across a meaningful period before deciding how much debt you can afford.
Review Your Credit
Check your credit reports for errors and understand your current obligations.
Ask lenders whether they use a soft credit inquiry for initial qualification and whether a formal application triggers a hard inquiry.
Borrow Only What You Need
A larger loan creates a larger repayment obligation.
Calculate the actual cost of the expense and request an amount that the business or household can realistically support.
Compare the Full Cost
Do not focus only on the advertised payment.
Consider:
- Interest rate or other financing charge
- Origination fees
- Administrative fees
- Total repayment amount
- Payment frequency
- Late fees
- Prepayment terms
- Collateral
- Personal guarantees
A financing product requiring less paperwork can still be expensive.
What If You Have No Verifiable Income at All?
If you have neither traditional income documentation nor reliable alternative records, obtaining conventional financing may be difficult.
In that situation, consider whether the expense can be delayed, reduced, or handled through another appropriate arrangement.
For a business, possible alternatives could include negotiating supplier payment terms, collecting outstanding invoices, reducing nonessential expenses, or building additional revenue history before taking on debt.
The important thing is not to replace a documentation problem with an unaffordable loan.
If a lender promises immediate approval despite having no meaningful information about your ability to repay, treat the offer cautiously.
Warning Signs to Watch For
Self-employed borrowers searching for easy financing may encounter advertisements that promise fast or guaranteed approval.
Be particularly cautious when a lender or broker:
- Guarantees approval regardless of financial circumstances
- Demands an upfront payment for guaranteed funding
- Refuses to provide complete written terms
- Hides fees or the total repayment amount
- Pressures you to sign immediately
- Requests unnecessary account passwords or sensitive information
- Encourages you to provide false income information
Never inflate revenue, falsify bank statements, or misrepresent your income.
Accurate information protects you as a borrower and helps ensure that any financing decision is based on your real financial situation.
Frequently Asked Questions
Can I get a loan if I am self-employed and do not have pay stubs?
Possibly. Some lenders accept tax returns, bank statements, invoices, or other forms of income verification instead of traditional pay stubs.
Can freelancers qualify for loans?
Yes, freelancers may qualify for personal or business financing if they meet the lender’s requirements. Documented income, credit history, business activity, and repayment ability may all matter.
Can I get a business loan without tax returns?
Some financing products may not require traditional tax returns, but the lender may use bank statements, transaction data, revenue records, or other information instead.
Does being self-employed automatically make loan approval harder?
Not necessarily. Self-employed borrowers can qualify for financing, but variable income and nontraditional documentation can make income verification different from that of salaried employees.
Should I use a personal loan to fund my business?
It depends on the loan terms, permitted use, and your ability to repay from personal finances. Business financing may be more appropriate for business expenses, while a personal loan creates a personal repayment obligation.
Conclusion
Self-employed borrowers may have financing options even when they do not receive traditional pay stubs. The key is understanding how a lender verifies income and which alternative records you can provide.
Bank statements, tax records, invoices, contracts, payment processor reports, and business financial statements may all help demonstrate financial activity, depending on the lender.
Before borrowing, separate personal and business needs, compare the full cost of financing, and make sure the payment fits your actual cash flow.
Most importantly, do not confuse “no traditional proof of income” with “no verification.” A responsible financing decision should always be based on a realistic understanding of how the debt will be repaid.
admin
Practical business guides, useful tools, and technology insights from BusinessNexa.
Work smarter with practical business tools.
Explore useful calculators, guides and tools for modern businesses.